Buying • Market Trends • Selling • October 1, 2026

What Higher Mortgage Rates Mean for Home Sellers

Higher mortgage rates don’t just affect buyers. They can change what it takes to sell your house, too.

That’s because today’s buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they’re looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that.

If you’re planning to sell, that doesn’t mean you can’t compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too.

Builders Are Competing on the Monthly Payment

New construction has something interesting going for it right now. While existing-home sales  (homes that have previously been lived in) continue to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better.

In a recent interview, Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels. On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels.

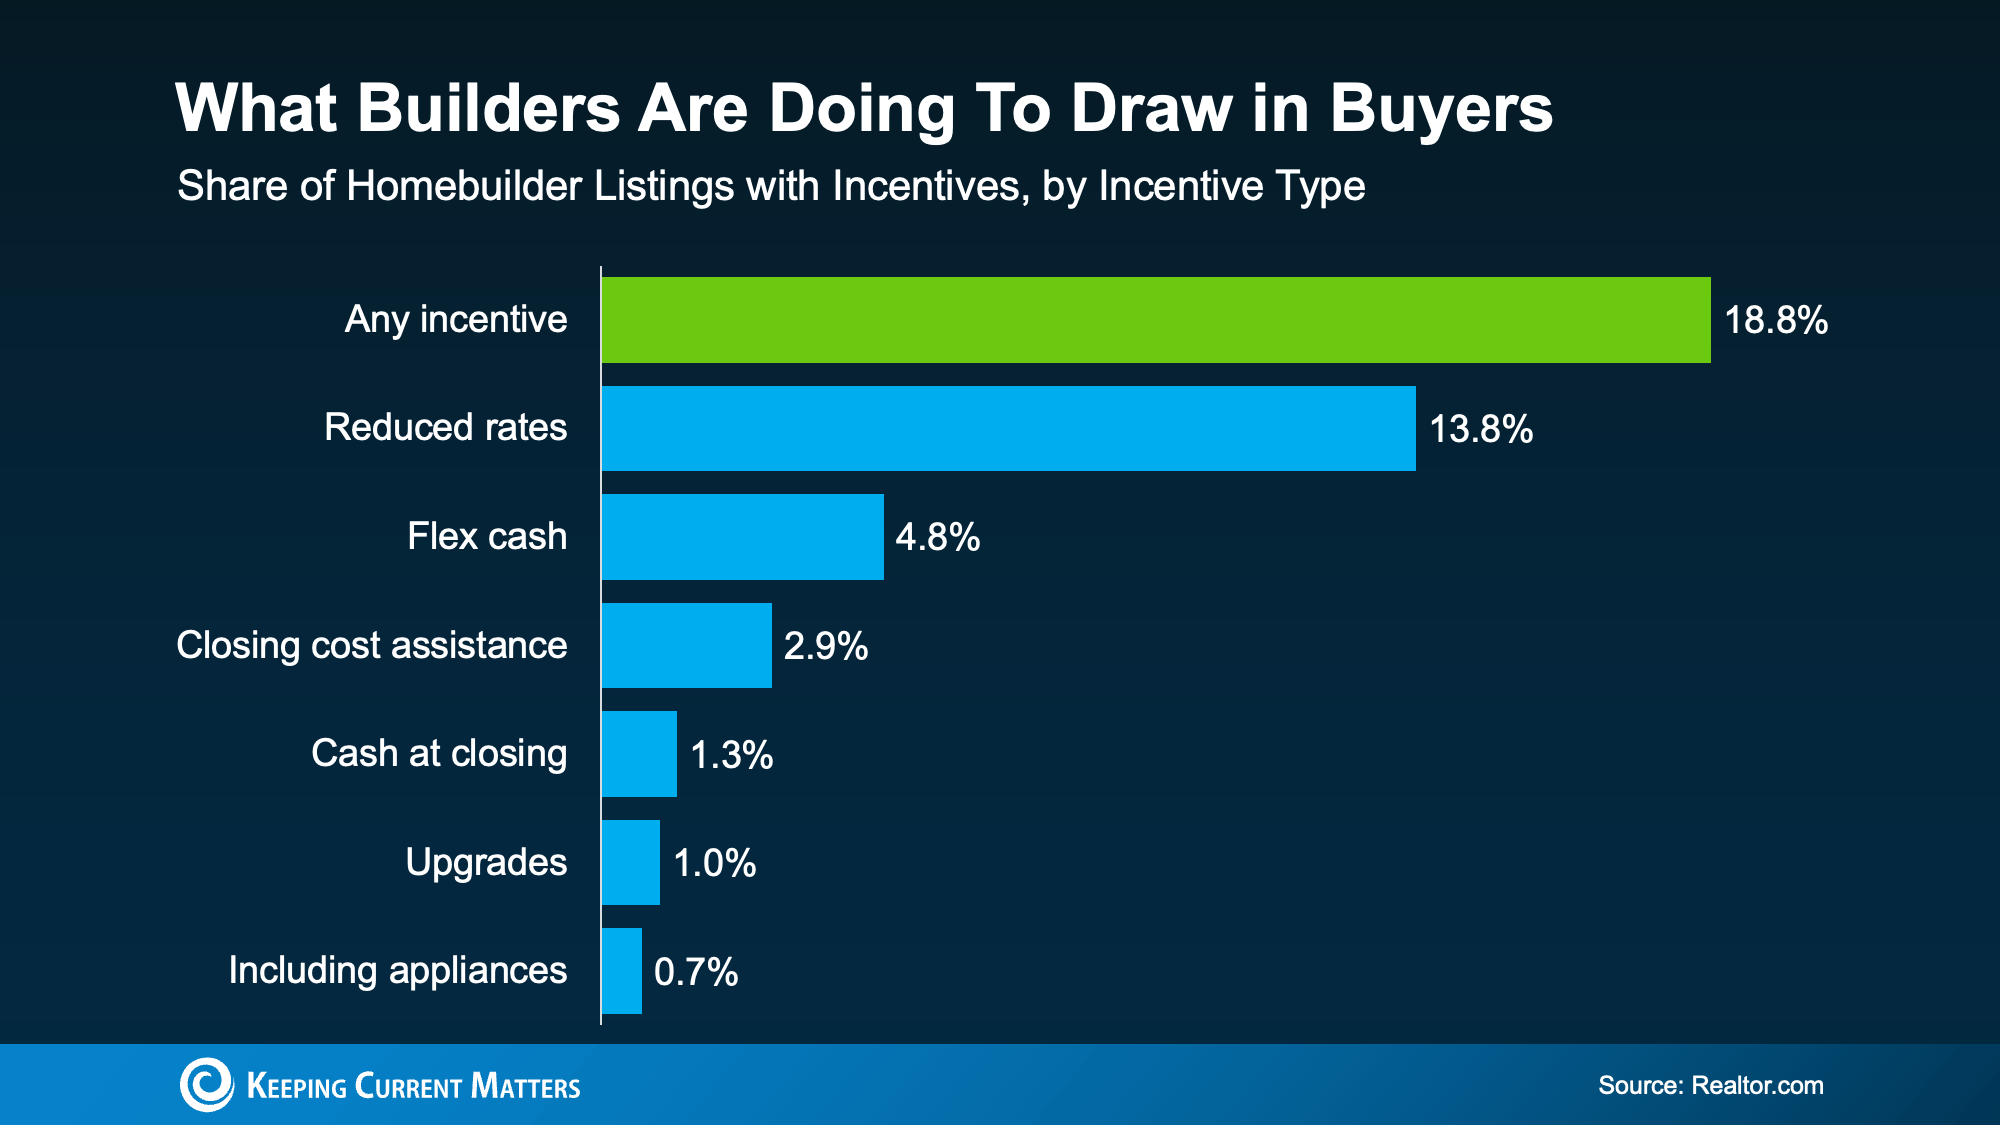
One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com, nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front:

a graph of a company's sales

The most common may surprise you. As the graph shows, many builders are offering reduced rates, sometimes through something called a mortgage rate buydown.

It’s essentially where they pay upfront costs to help buyers get a lower rate, and by extension, a lower monthly payment. It has obvious draws for buyers. For homebuilders, it helps them get their houses sold. So, a lot of builders see it as a win-win. That’s why reduced rates are a part of 13.8% of new home listings.

In some cases, builders are offering rates below 6%, maybe even far below 6%. And that can help buyers shave hundreds off their monthly payment. That’s a big difference to a buyer who are feeling the pinch right now.

So, How Can Sellers Like You Compete?

First, don’t assume a mortgage rate buydown is something only a builder can offer. Sellers can contribute toward a buyer’s rate buydown too, depending on the loan and transaction. Does that mean you should offer one? Or that you have to if you want to compete? Not necessarily.

A buydown is just one possible lever. Depending on your market and the buyer, it may make more sense to negotiate on price, contribute toward your buyer’s closing costs, make repairs, or make sure your house stands out in ways a new build can’t. That’s why working with an agent who knows your local competition matters. Joel Berner, Senior Economist at Realtor.com, says:

“Sellers of existing homes are facing a lot of competition from the new-home space. . . so sellers should highlight the local amenities of their neighborhoods in contrast to the more suburban or exurban communities where many new homes are built.”

A great agent will do this naturally anyways. Knowing what makes your house different and showcasing that in your listing can help your house stand out. And remember, being open to making a few compromises or throwing in some concessions can make a bigger difference for buyers than you may think.

Today’s Market Rewards Sellers Who Adapt

Builders have also been quicker to adjust their prices based on what buyers can actually afford and where demand is. That’s putting pressure on the resale market in some areas. Robert Dietz, Chief Economist at the National Association of Home Builders (NAHB), explains:

“. . . existing homeowners now have to do the price discovery that builders have been doing since 2022.”

That’s an important message if you’re hoping to sell.

You don’t automatically need to slash your price or offer a big concession. But you do need to price and market your house based on what buyers can pay today – not what sellers could get a few years ago.

And remember, this varies tremendously by location. New construction represents a much bigger share of the competition in some markets than others, and builder incentives aren’t equally common everywhere. So, lean on an agent to see how big of a factor builders are in your area.

Bottom Line

Higher mortgage rates are making buyers more cost-conscious. Builders know that, and many are responding with rate buydowns, closing-cost help, price reductions, and other incentives.

If you’re thinking about selling, give me a call to talk about what buyers are getting from other homes in our area – including new construction – so you can make sure your house is positioned to compete.

Buying • September 23, 2026

3 Things You Can Actually Control About Your Mortgage Rate Right Now

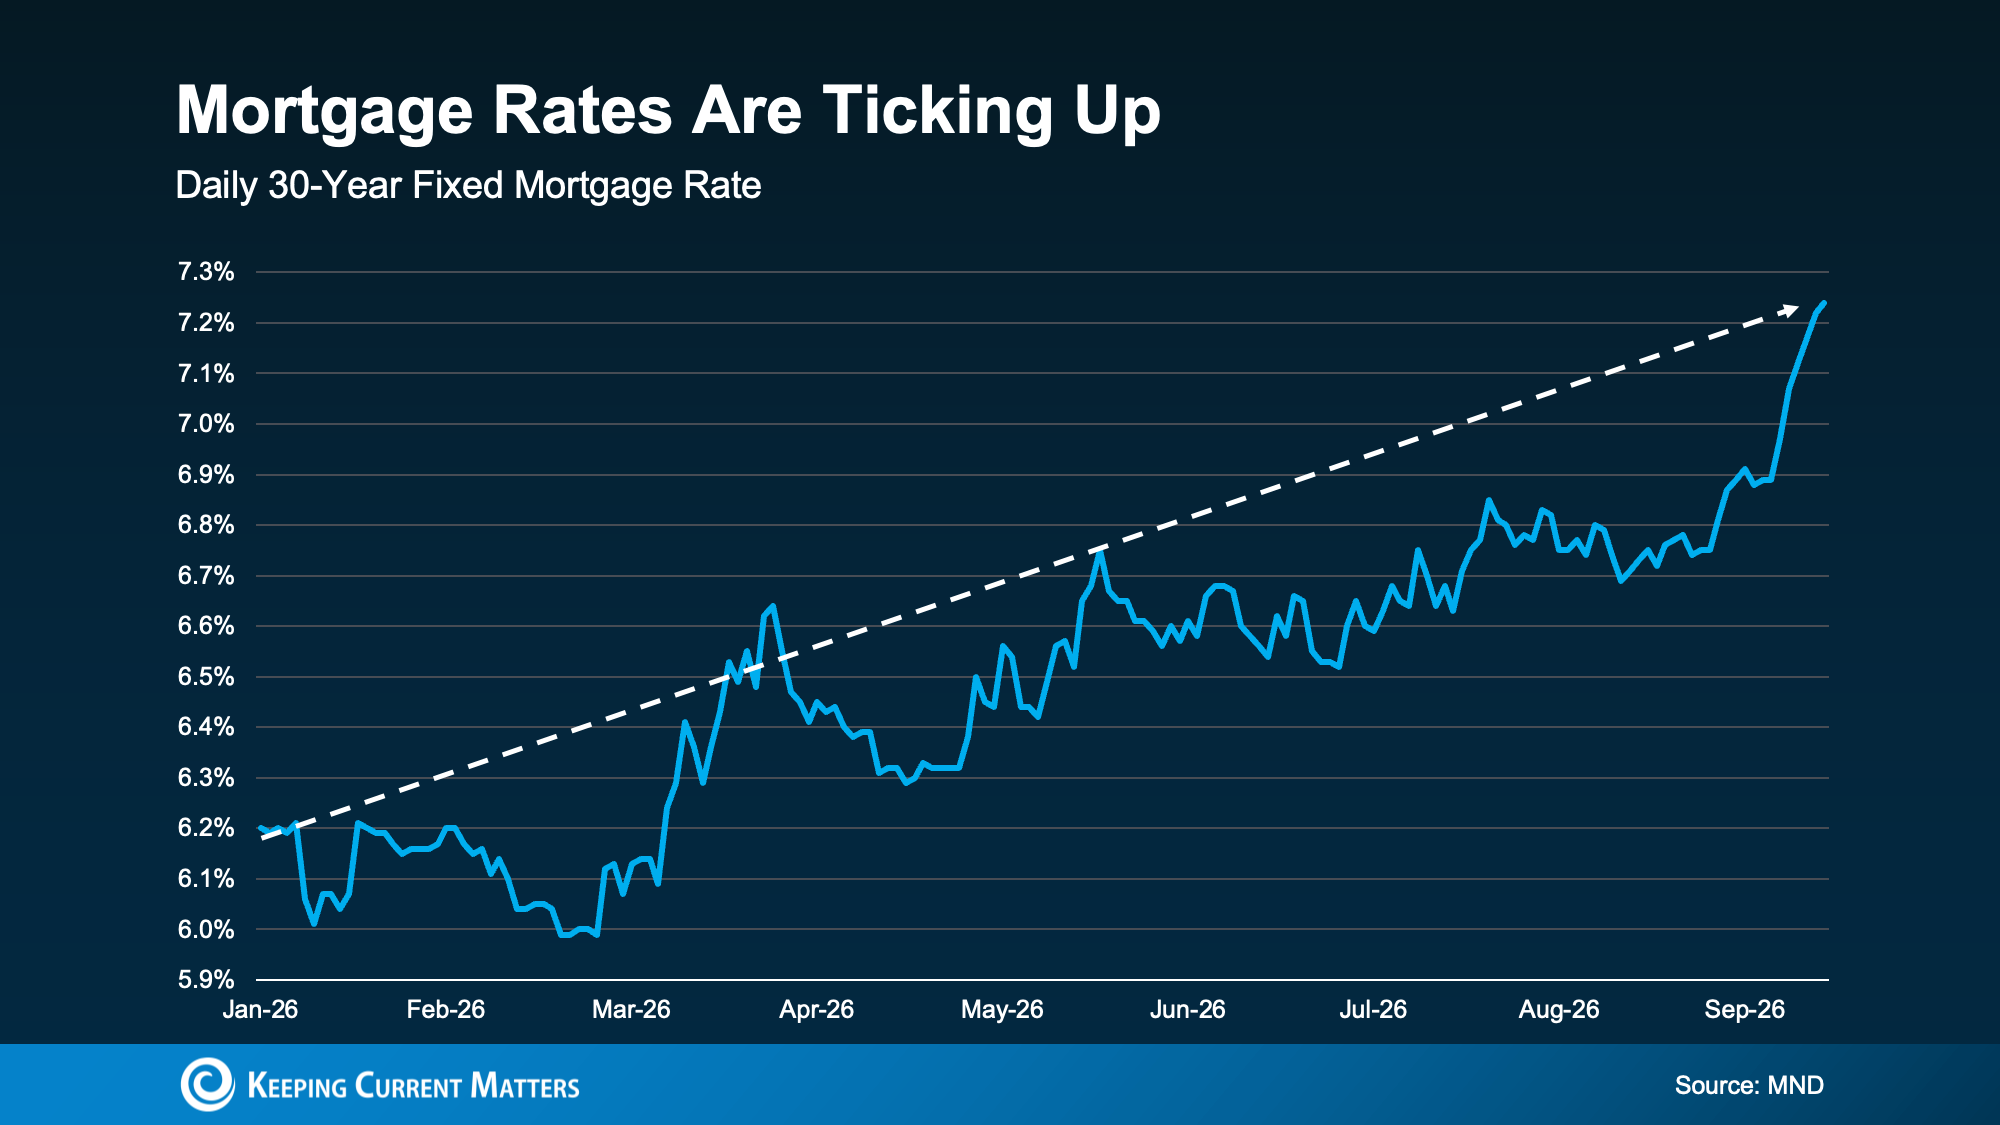
If you’re trying to buy a home, affordability is probably what keeps you up at night. And as you watch mortgage rates tick up again lately, it’s fair to wonder if you should just hit pause and wait for them to go down.

For now, though, they’re headed the other way. Mortgage News Daily data shows how rates have risen this year (see graph below):

a graph of a moving rate

And if you’re wondering why? There are actually a number of reasons.

Mortgage rates are impacted by the situation overseas, economic data, inflation numbers, oil prices, and even decisions from the Federal Reserve (who recently decided to hike their Fed Funds Rate – which often affects mortgage rates too). As Danielle Hale, Chief Economist at Realtor.com, explains:

“The pressure on mortgage rates was here even before the Fed rate hike, and it doesn’t show signs of relenting. . .”

Now, that’s probably not what you wanted to hear. But, it doesn’t mean there’s nothing you can do. While you can’t control where rates go from here, you absolutely can control several things that shape the rate you actually get.

So where should you focus? Let’s walk through it.

Work on Your Credit Score

Your credit score plays a big role in the rate you qualify for, and even a small improvement can make a real difference in your monthly payment. As Freddie Mac puts it:

“Generally, the higher your credit score the more options will be available to you, including better loan terms and a lower interest rate.“

So, make sure you do what you can to keep your credit score up. If you’re not sure where your score stands right now, or how to improve it, talk to a trusted loan officer.

Explore Your Loan Options

The type and term of your loan both affect your rate. Conventional, FHA, VA, and USDA loans each come with their own requirements and rates, and your term (15, 20, or 30 years) changes both your payment and the total interest you’ll pay. The structure matters, too. A fixed-rate loan holds the same rate over time, while an adjustable-rate loan usually starts lower and can move later on. Bankrate explains it this way:

“. . . rates on fixed-rate loans are typically higher than introductory rates on adjustable-rate loans because the fixed-rate lender takes on the risk that rates could increase during the loan’s term. Likewise, government-backed FHA, VA and USDA loans sometimes have lower rates because they have a government guarantee or insurance that cuts the lender’s risk.“

It’s important to explore your options with a lender to see what makes the most sense for you. Just be sure to balance your goals, your possible rate, and any potential tradeoffs before making any decision. You may even want to talk to multiple lenders to see how the options vary.

Consider a Newly Built Home

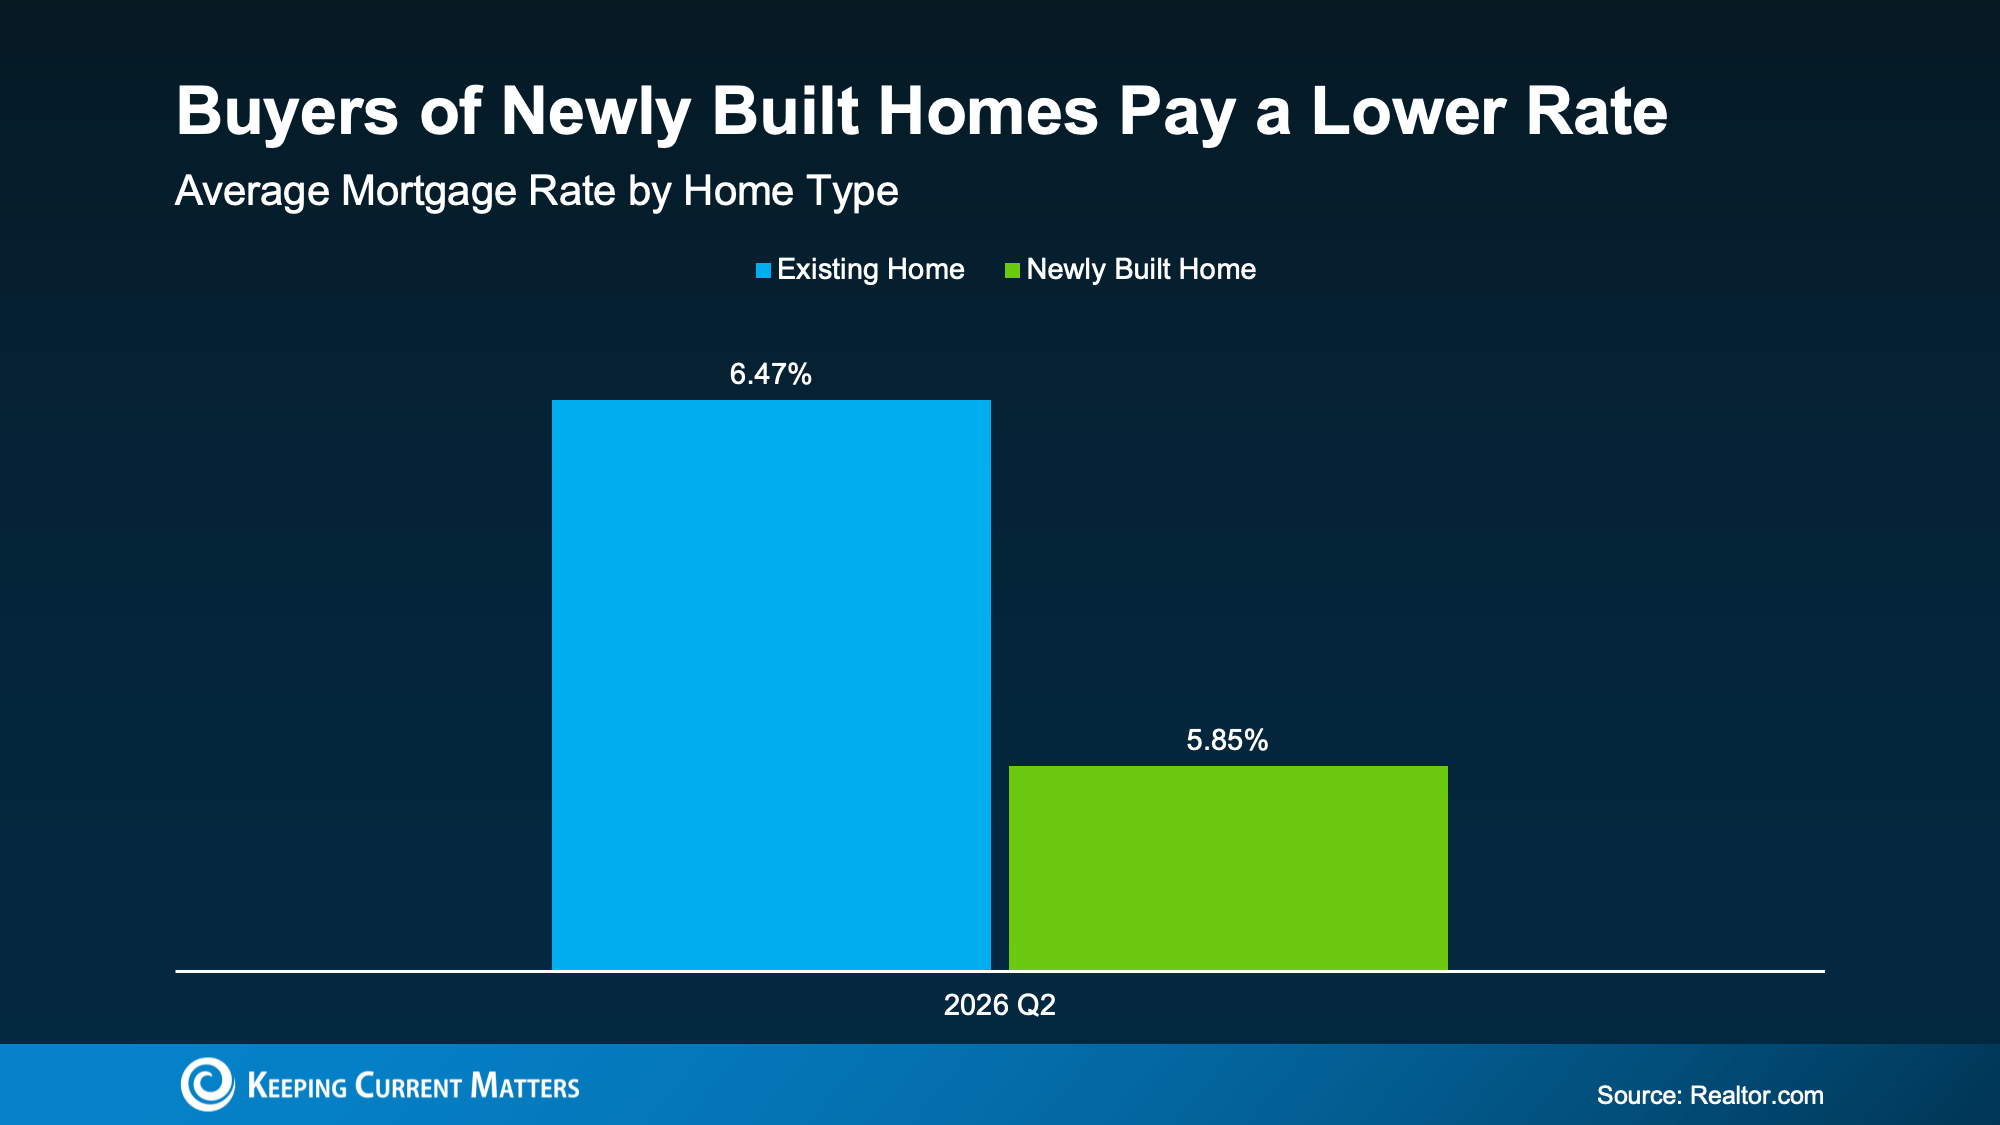
Another path to a lower rate comes down to the kind of home you buy. Many builders are buying down mortgage rates, which lowers your monthly payment. It’s just one way they’re trying to attract buyers and get their homes sold.

According to Realtor.com, buyers of newly built homes landed a lower average rate last quarter than buyers of existing homes (see graph below):

a graph of a graph showing a number of houses

If a lower rate is your goal, it may be worth asking your agent to show you some new build communities that are offering this type of incentive locally.

Bottom Line

You can’t control where mortgage rates go, but you can control your credit, your loan, and the kind of home you buy. Working with a trusted lender can help you lock in the best rate you qualify for. And when you’re ready to make a move that fits your budget, give me a call.

Buying • September 9, 2026

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.

Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is.

Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.

Why Dipping into a 401(k) Can Be Tempting

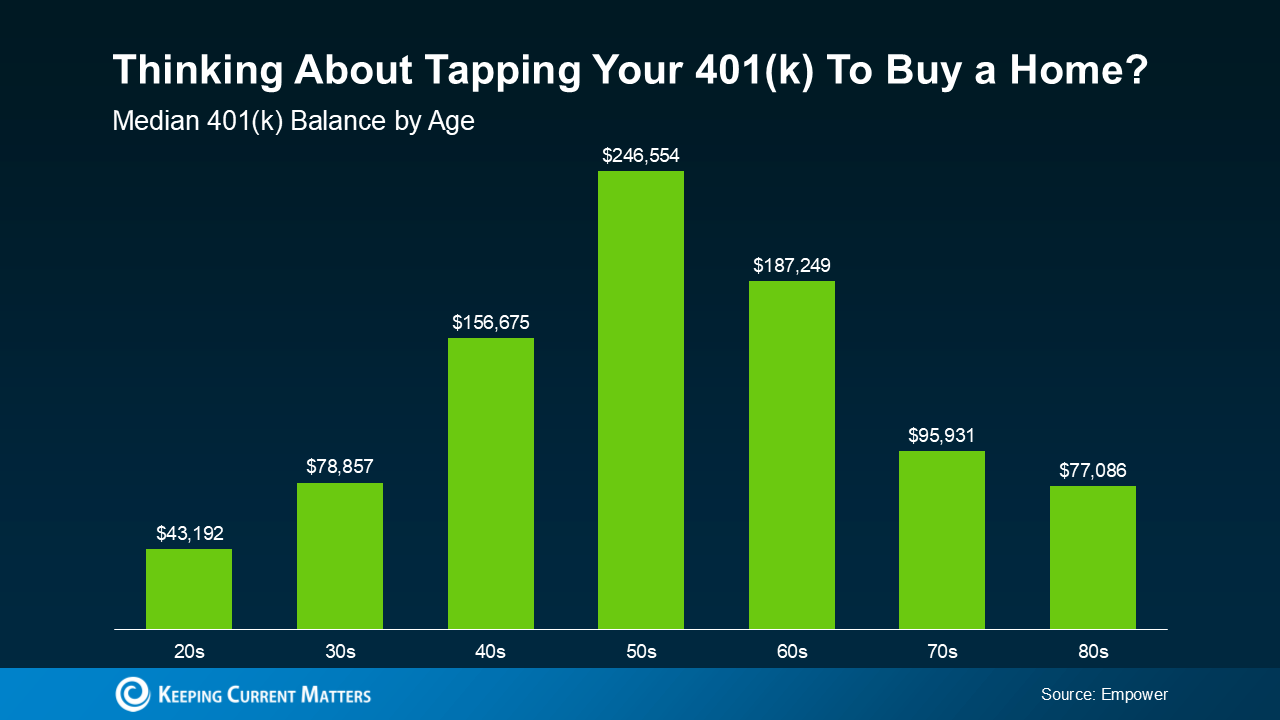
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):

a graph of green bars

And when you’ve got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.

But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That’s why it’s a good idea to explore other options for your down payment first. As Redfin says:

“If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.“

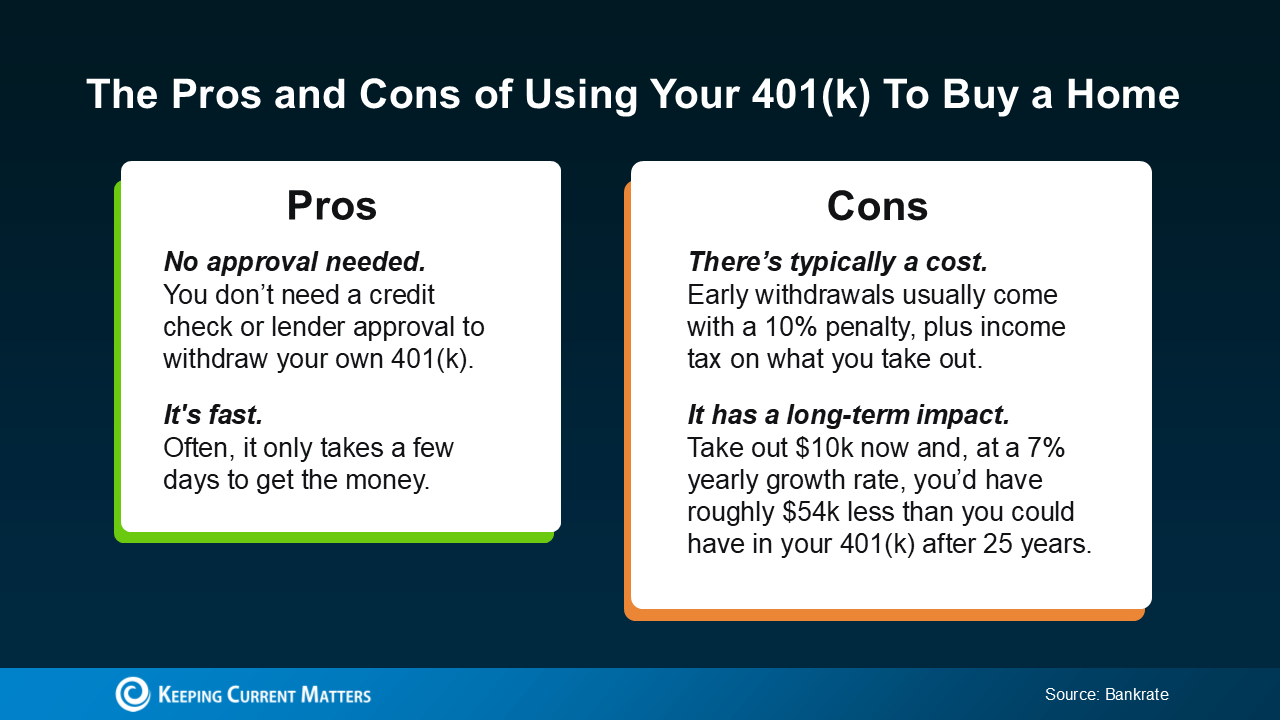
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):

a screenshot of a computer screen

Other Options Worth Exploring First

Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:

  • Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home’s price, depending on their credit scores.
  • Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.

Make a Plan Before You Make a Move

No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:

“Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.“

Bottom Line

Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.

If you’re considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget.

Market Trends • September 3, 2026

Placer County Real Estate Market Update: September 2026

The Placer County housing market is heading into fall with stable home prices, declining inventory and a slight advantage for sellers.

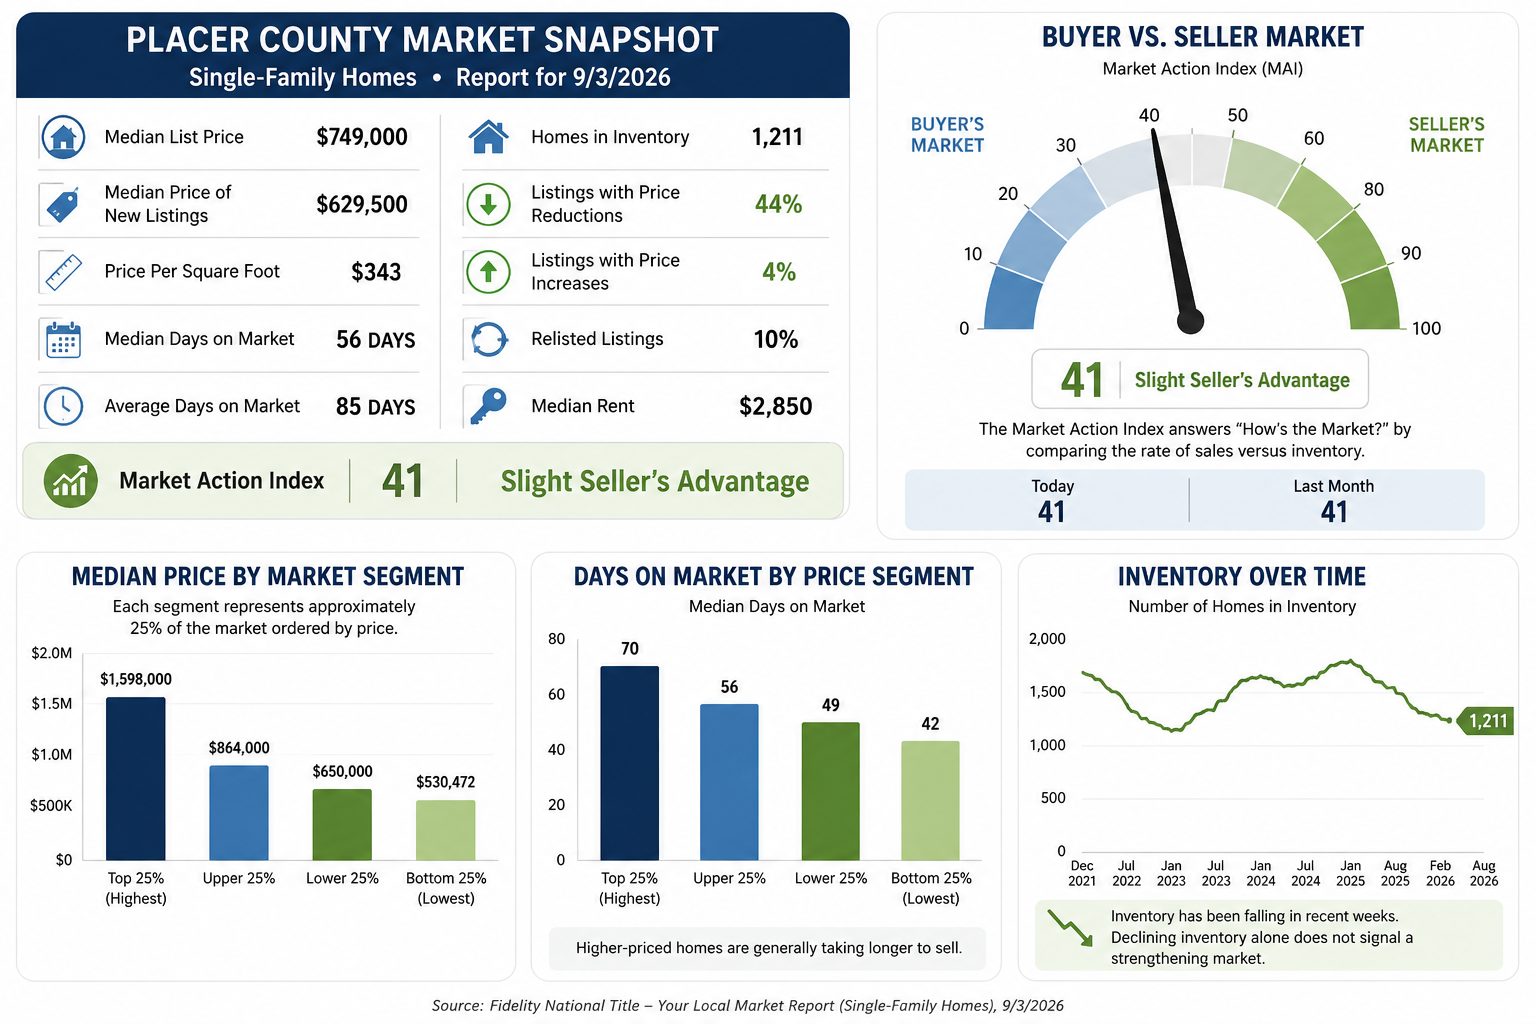
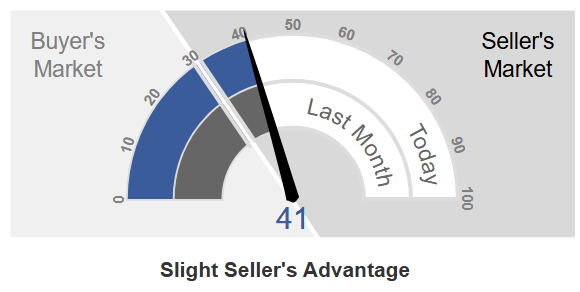
As of September 3, 2026, the median list price for a single-family home in Placer County is $749,000. There are 1,211 homes on the market, and the Market Action Index is 41, indicating a slight seller’s advantage.

What is the Placer County housing market like right now?

Placer County is currently experiencing a slight seller’s market, although buyers still have negotiating opportunities.

Here’s a quick look at the latest numbers:

Placer County Market Statistic September 2026
Median List Price $749,000
Median Price of New Listings $629,500
Price Per Square Foot $343
Homes in Inventory 1,211
Median Days on Market 56 days
Average Days on Market 85 days
Listings with Price Reductions 44%
Market Action Index 41


Are Placer County home prices going up or down?

Home prices are relatively stable. The report describes the median list price as hovering around a plateau, rather than showing a strong upward or downward trend.

Price per square foot is also relatively steady at $343, reinforcing the overall picture of a market where values are holding fairly consistent.

Are sellers reducing their prices?

Yes. 44% of current Placer County listings have had a price reduction.

For sellers, this is an important reminder that pricing correctly from the beginning matters. Buyers are watching comparable properties closely, and homes priced above the current market may take longer to sell.

For buyers, price reductions can create opportunities to negotiate, particularly on homes that have been available for several weeks.

How long are homes taking to sell in Placer County?

The median days on market is currently 56 days, while the average is 85 days.

How quickly a home sells also depends on price range. The report shows median days on market ranging from approximately 42 days in the lowest-priced quarter of the market to 70 days in the highest-priced quarter.

Is Placer County a buyer’s or seller’s market?

Placer County currently has a slight seller’s advantage.

The Market Action Index is 41, unchanged from last month. Inventory has also been declining in recent weeks. The report notes that sales are continuing to outpace supply, which could put additional upward pressure on prices if the trend continues.

That doesn’t mean buyers are without leverage. With 44% of listings experiencing price reductions and homes taking longer to sell than in highly competitive markets, there may still be room for negotiation.

What does this mean for Placer County buyers and sellers?

For buyers: You may have more time to evaluate homes and negotiate on properties that have been sitting on the market or have already reduced their price.

For sellers: Demand remains healthy, but buyers are price-conscious. Accurate pricing, strong presentation and effective marketing are especially important in the current market.

Most importantly, Placer County is made up of many smaller markets. Conditions in Roseville, Granite Bay, Rocklin and surrounding communities can vary significantly by neighborhood, property type and price range.

What is my Placer County home worth in today’s market?

Online estimates and countywide statistics are a helpful starting point, but they don’t account for your home’s specific location, condition, upgrades or current competition.

If you’re considering selling your home, I can prepare a personalized market analysis using recent sales and active listings in your neighborhood to help you understand where your property fits in today’s market.

Suzanne Volkman
Broker Associate | Coldwell Banker Realty

Market statistics are based on the September 3, 2026 Fidelity National Title Local Market Report for Placer County single-family homes.

Selling • August 25, 2026

One Number Could Change Everything About Your Next Move

When’s the last time someone told you what your house is worth? Not what some online valuation tool guessed. Not what your neighbor’s house sold for. What yours is actually worth right now.

For a lot of homeowners, it’s been years. And if you’ve been thinking about moving, but higher home prices or mortgage rates have made you hesitate, here’s why it’s time to take a second look at that number.

Your House May Be Worth More Than You Think

Home values have climbed significantly over the past 5-10 years. And even though today’s market is more balanced, homeowners are building wealth every day just by owning their homes. That’s how equity works. As home values rise, and as you make your monthly payments, your equity grows. And it adds up fast.

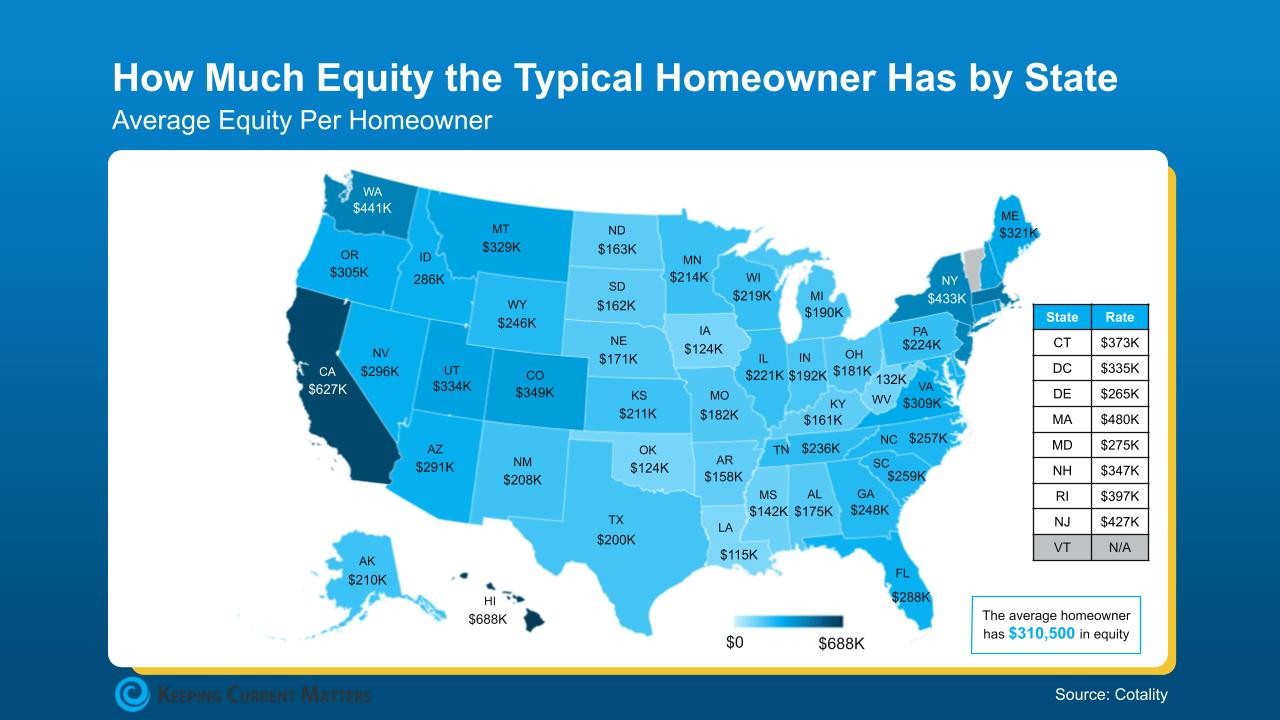
According to Cotality, the typical homeowner with a mortgage now has $310,500 in equity. That’s not a small number. It’s six figures.

And that’s only the national average. In many states, homeowners have built even more equity than that. Take a look at the map below and see where your state stands. The darker the blue, the more equity the typical homeowner has there (see map below):

a map of the united states

Even though every local market is different, the question you should be asking right now is the same: How much equity have you built up?

Because if you don’t know that number, you’re missing out.

This Could Be the Missing Piece in Your Move

Most people assume that because prices are higher and rates aren’t at 3% anymore, moving just isn’t realistic right now, especially if they already have an ultra-low rate. And that’s understandable – those are real factors.

But they’re not the only factors.

When you have that much equity in your house, you’re not starting from scratch. You’re not scraping together a down payment or hoping the numbers work. You’re walking into your next move with more of an advantage than you think. And that changes the math.

What Your Equity Can Do for You

Maybe you’ve outgrown your current house or you’re ready to downsize… The equity you’ve built could help bridge the gap between where you are today and where you want to be next.

Yes, your next house may cost more than your last one did. But your equity could cover a big chunk of that difference. Depending on how much you’ve built, it could help you:

  • Lower your monthly payment on your next home. The bigger your down payment on your next place, the less you have to borrow. And with today’s rates, borrowing less can make a big difference in what you pay every month.
  • Buy your next house with all cash. This surprises a lot of people, but some homeowners have built enough equity to buy their next home outright, in cash. According to the National Association of Realtors, more than one-quarter (26%) of repeat buyers paid all cash for their home in July.
  • Transform the home you already have. Love your neighborhood but not your floor plan? You don’t have to move. Your equity could help fund renovations that make your home fit your life today while potentially adding value for tomorrow.

Your equity doesn’t erase the challenges of the current market. But it does mean you’re walking into your next move with a lot more power and flexibility than you think.

That’s why the value of your home isn’t something you should have to wonder about. 

If you’re even thinking about a move – or if you’re just curious what your options might be – the smartest thing you can do is get a Professional Equity Assessment. It’ll give you a real, market-based evaluation of what your house is really worth right now and how much equity you’re working with.

Because once you see the number, maybe it’s not about whether you can afford to move – it’s about what kind of move makes sense for you.

Bottom Line

If it’s been a while since you’ve gotten a professional look at your home’s value, it’s time to change that.

Give me a call for a free, personalized Home Equity Assessment that estimates what your house could sell for, how much equity you’ve likely built, and what that could mean for your next move.

You may have six figures of equity without even realizing it. And that’s enough to change everything about your next move.

Buying • Lending • August 13, 2026

Thinking About Waiting for Lower Mortgage Rates? Read This First.

Imagine waiting a year to buy a home, only to find mortgage rates haven’t changed much. That may sound frustrating.But it’s a real possibility.

A lot of people are putting their plans on hold because they believe much lower mortgage rates are right around the corner. But, based on today’s forecasts, that may not happen. And you should know that before you decide what to do.

Let’s look at why experts don’t expect a dramatic drop in rates – and the options that could help you buy anyway. Because even if rates don’t fall, you can still move. Here’s how.

1. Mortgage Rates Aren’t Expected To Fall in a Meaningful Way

If you’re waiting for rates to fall, you’re not alone. A recent survey from Clever-Best Interest found 42% of people believe mortgage rates will drop below 5% this year.

The challenge is, that’s not what the experts who study mortgage rates every day are expecting.

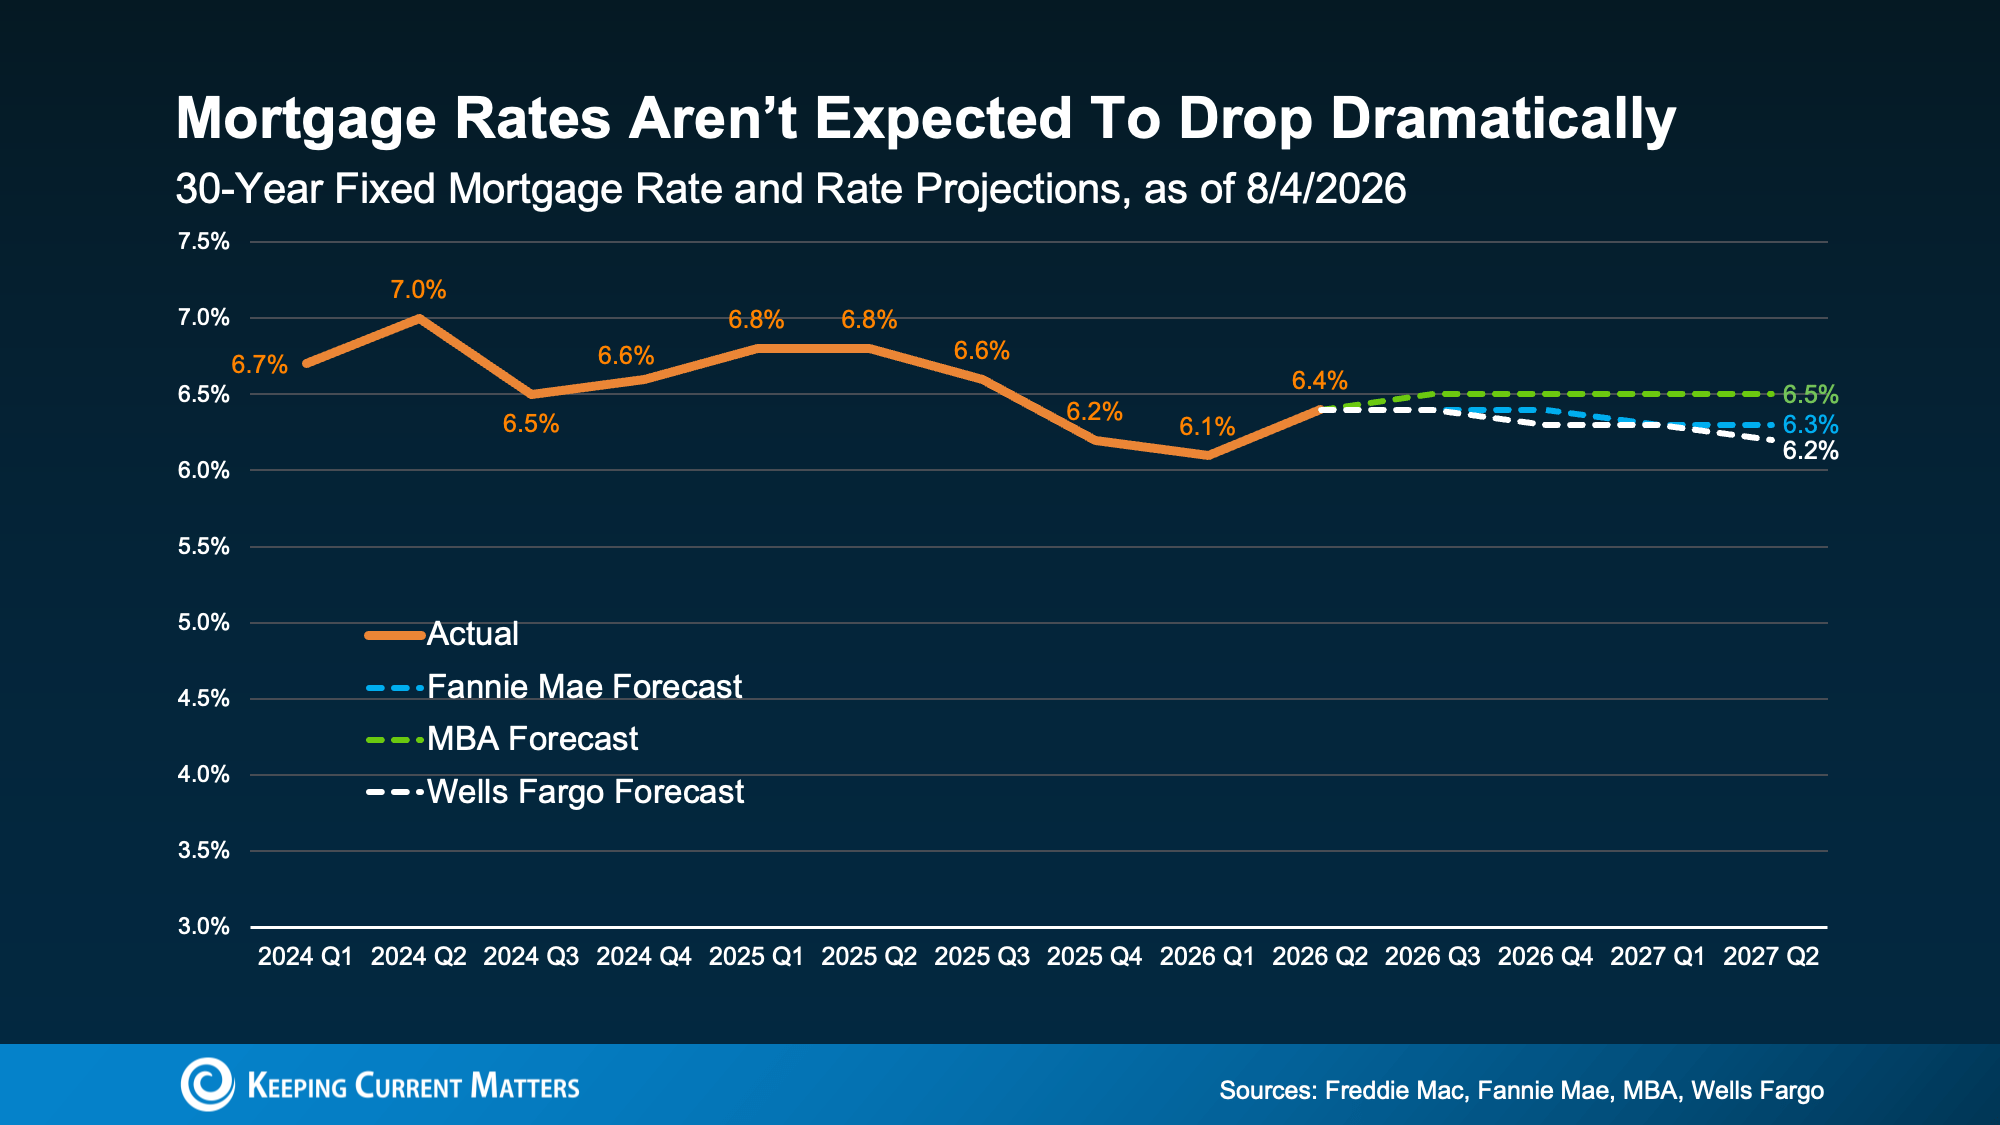
Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all show mortgage rates staying relatively steady in the low-to-mid 6% range through at least mid-2027 (see graph below):

a graph with numbers and lines

Why? Rates are influenced by inflation, the overall economy, Treasury yields, Federal Reserve policy, global events, and a lot of other moving pieces. And right now, those factors simply aren’t pointing toward the kind of dramatic rate drop many buyers are waiting for.

Could rates move a little? Of course. But if you’re holding out for a bigger drop, today’s forecasts suggest you may be waiting a lot longer than you expect.

2. Inflation Is Still Elevated – And That’s Working Against Lower Rates

One reason experts aren’t expecting rates to fall much? Inflation. Generally speaking, high inflation is the enemy of lower mortgage rates.

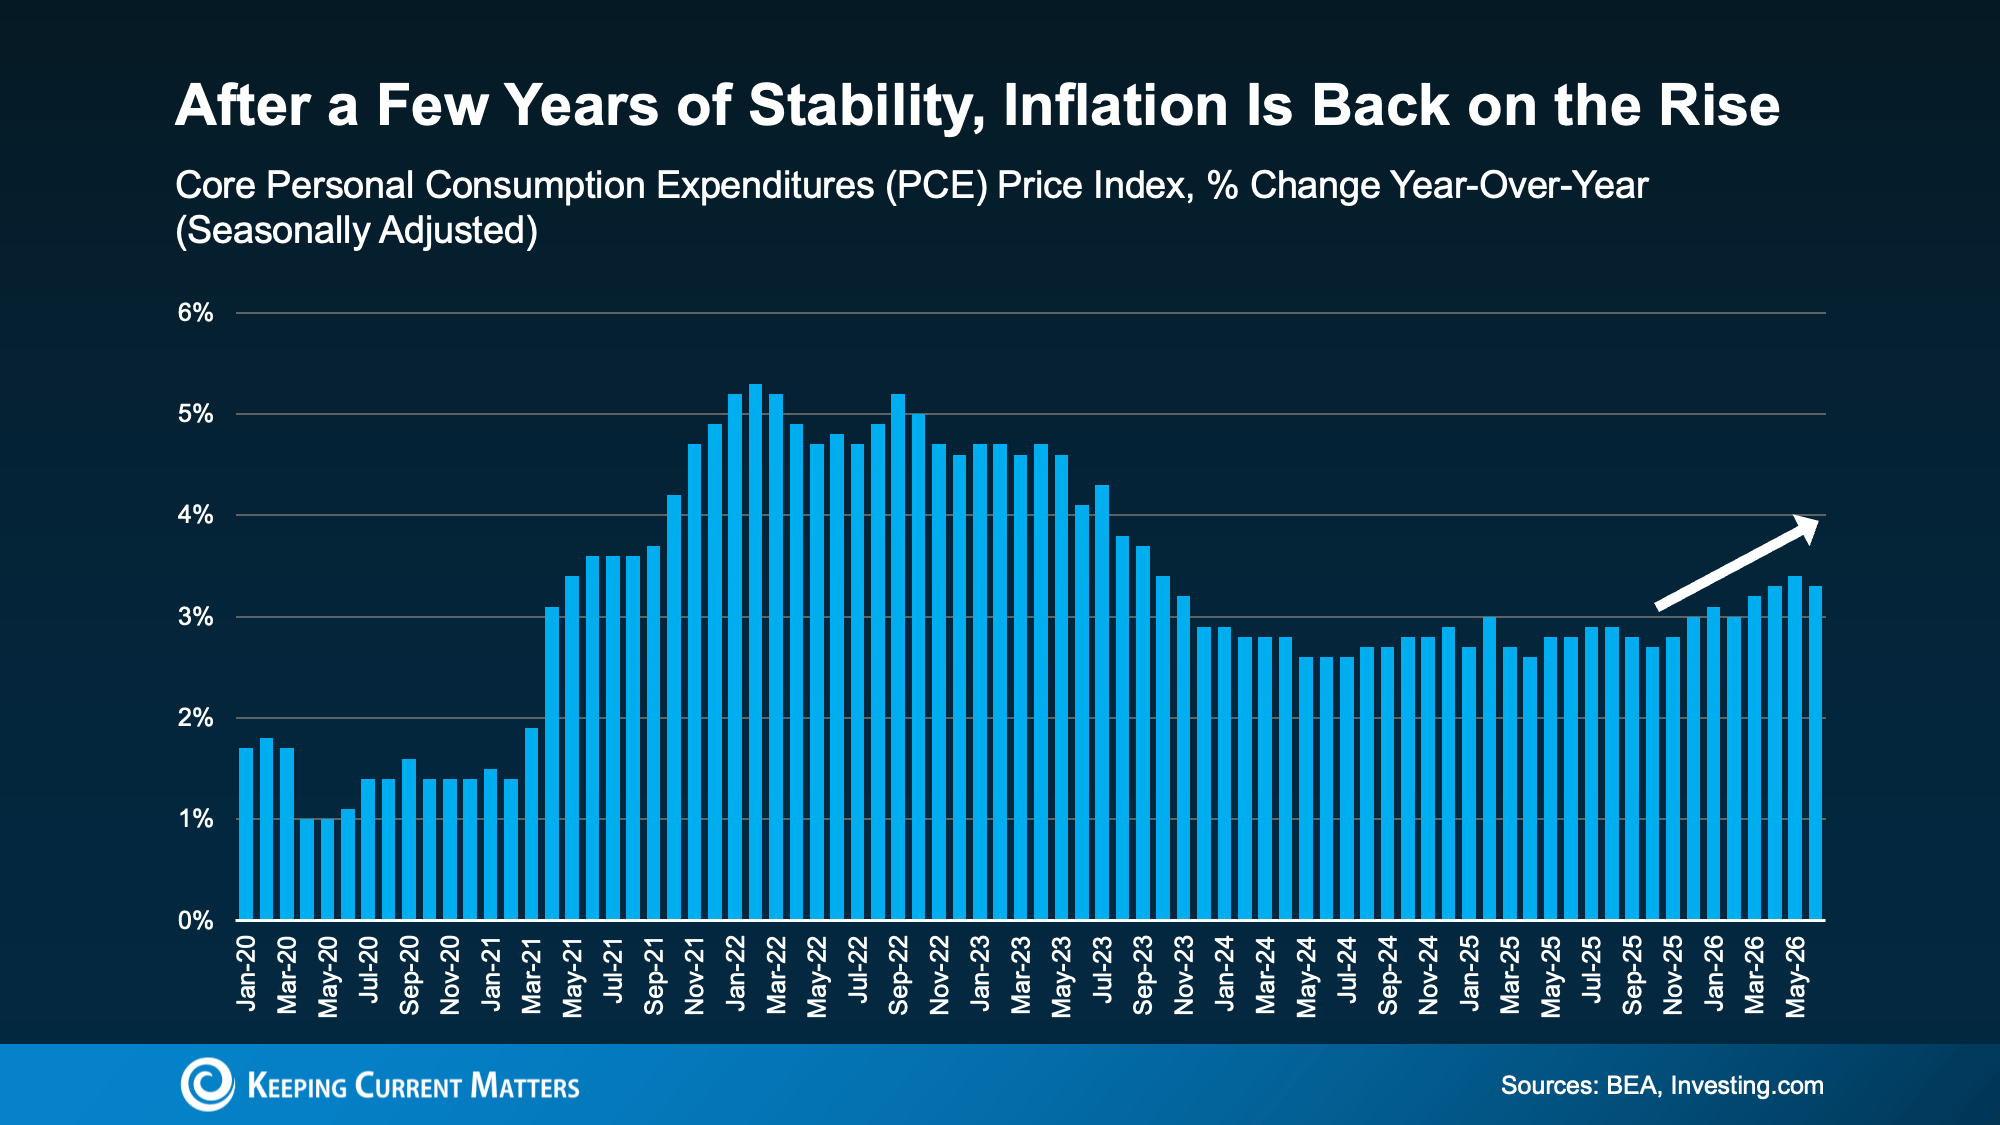
And after a period of relative stability from mid 2023 to late 2025, recent data shows inflation has actually been trending higher lately (see graph below):

a graph of a number of people

In other words, one of the biggest ingredients needed for much lower mortgage rates simply isn’t in place today. That helps explain why experts aren’t forecasting the kind of meaningful decline so many buyers are hoping for.

3. Today’s Rates Aren’t High, They’re “Normal”

And this may be the biggest mindset shift of all. The reality is, while today’s rates may feel high compared to a few years ago, they’re not high. They’re normal.

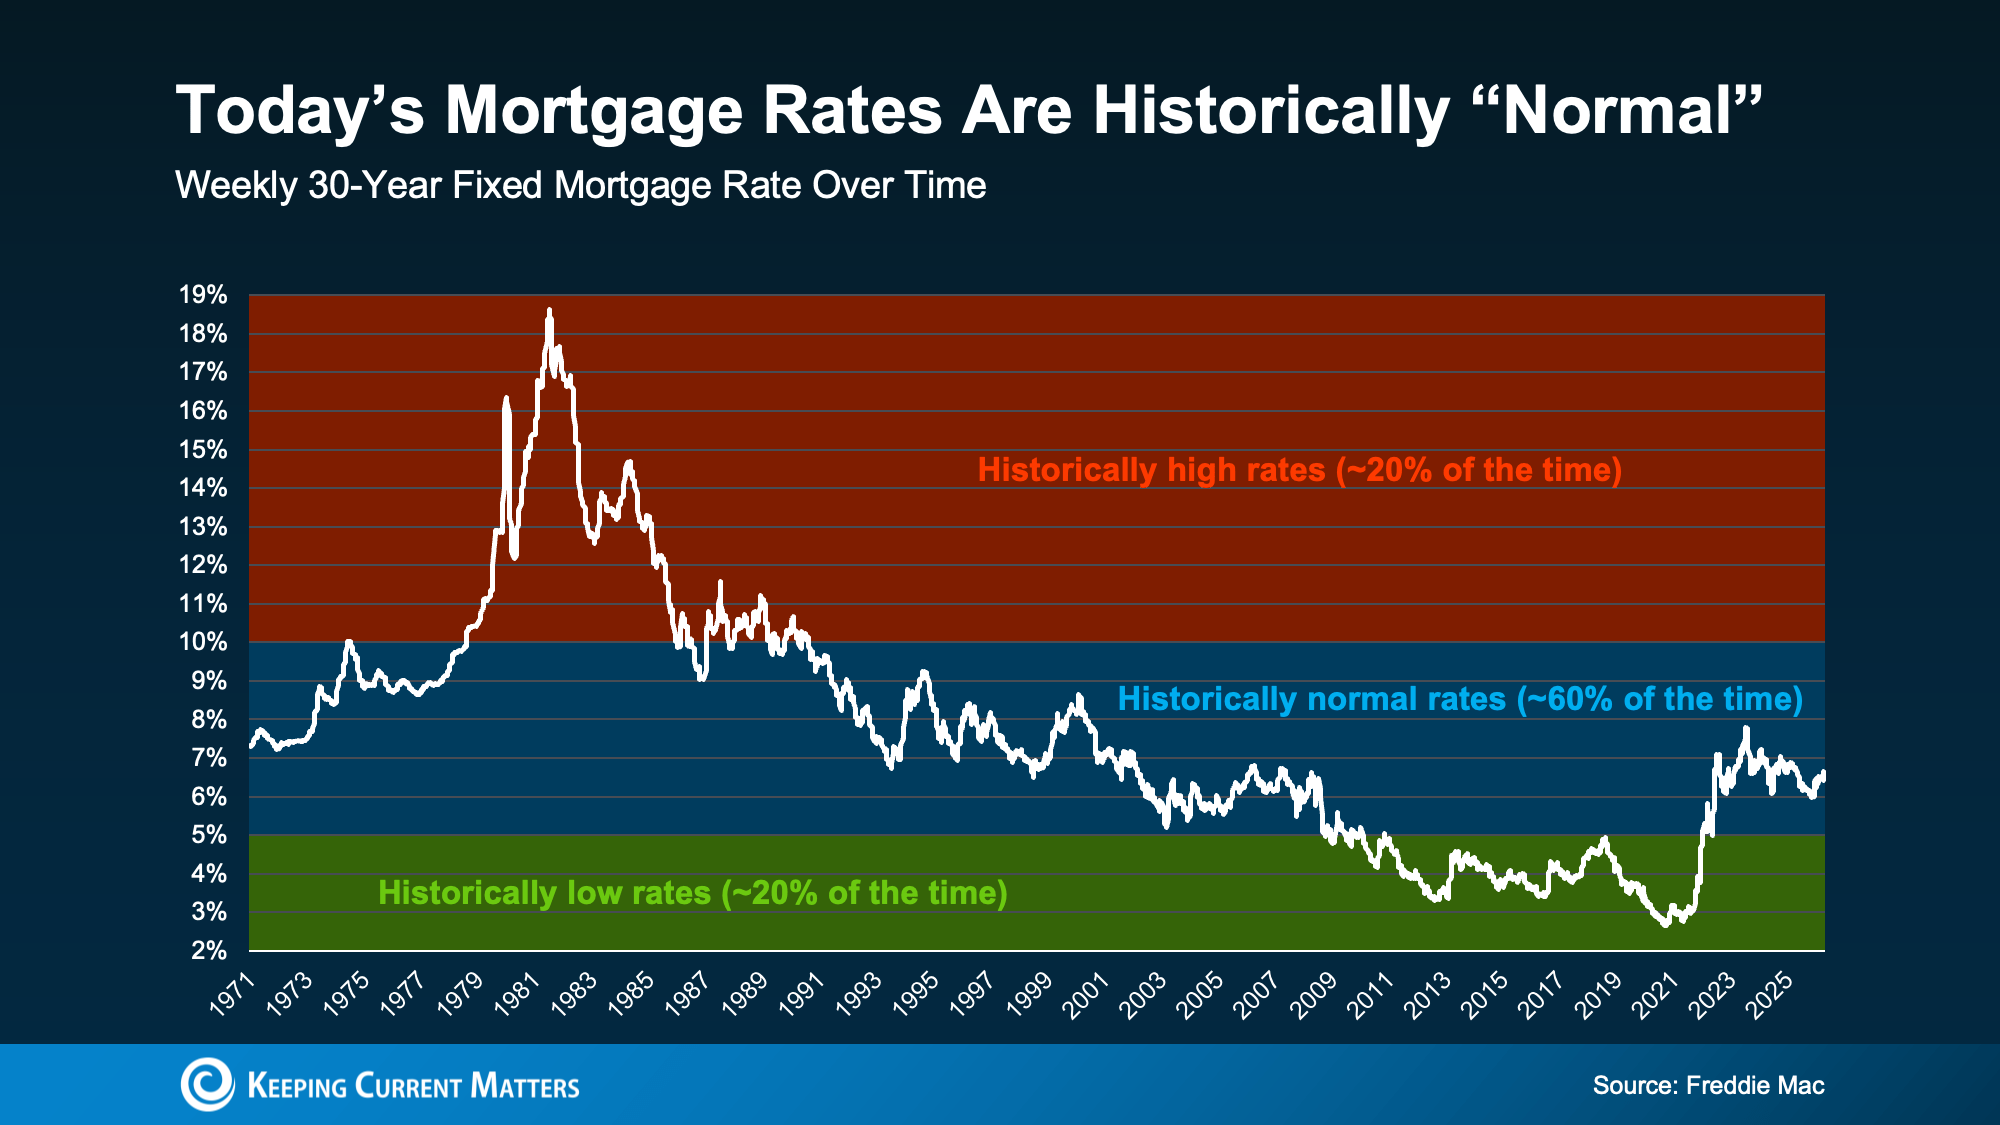
Historically, mortgage rates have spent the majority of their time somewhere between about 5% and 10%. And data from Freddie Mac shows we’re actually well in that range today. It just feels high because we all remember the ultra-low rates homeowners got during the pandemic (see graph below):

a graph of a graph showing the rise of a mortgage rate

Now, this doesn’t suddenly make a 6% mortgage feel exciting. But it does remind us that waiting for super low rates again may not be a realistic strategy.

So… What Should You Do Instead?

None of this is meant to convince you that you have to buy today. You don’t. But if you need to because something in your life’s changed, there are still ways to find better affordability without waiting for mortgage rates to fall.

  • Check out newly built homes. Many builders are offering incentives to attract buyers, including price cuts, potentially lower rates, free upgrades, and more.
  • Ask about an adjustable-rate mortgage (ARM). If you don’t plan to stay in the home long-term, an ARM may offer a lower initial interest rate than a traditional 30-year fixed mortgage. It’s not the right choice for everyone, but it’s worth asking a lender if it fits your plans.
  • Look into mortgage rate buydowns. This is when you pay upfront to reduce your mortgage rate so you can get for a lower monthly payment without waiting for rates to fall.
  • Find out about assumable mortgages. An assumable mortgage allows you to take over the seller’s existing loan, including its lower mortgage rate.

The important thing is you shouldn’t assume waiting is your only option.

Talk with your real estate agent and lender about whether one of these strategies could be a good fit for you.

Bottom Line

If you’ve been putting your home search on hold because you’re convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.

Give me a call so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer.


Keeping Current Matters

Market Trends • Selling • August 5, 2026

The “Zillow Tax”: Why Homes on Zillow Sold for 1.3% Less

When it comes to selling your home, every decision matters—including where and when your property is marketed. For years, many homeowners have assumed that getting their home on Zillow as quickly as possible was the key to attracting buyers and achieving the highest price. However, emerging research is challenging that long-held belief.

The report below takes a closer look at how public listing sites can influence buyer perception, negotiating leverage, and ultimately a home’s sale price. Whether or not you agree with every conclusion, it raises important questions about the value of a thoughtful marketing strategy versus simply maximizing online exposure from day one.

As a real estate professional, I believe homeowners deserve to understand all of their options before making one of their largest financial decisions. An informed seller is an empowered seller. I encourage you to read the research below and consider how a strategic, phased marketing approach may help protect your home’s value and put you in the strongest possible negotiating position.

Suzanne

*************************************************
Compass International Holdings Market Research


For years, Zillow has led sellers to believe that getting their home on Zillow.com quickly was important to sell their home. But new research analyzing over 300,000 homes revealed: homes on Zillow consistently sold for less. We call this loss the “Zillow Tax.”


The Hidden Cost of Listing on Zillow


To understand the financial impact of listing on Zillow, Compass Chief Economist Mike Simonsen and Chief Data Officer Dave Crosby analyzed the performance of listings that did not appear on Zillow, and compared them to nearly 300,000 listings that did. The analysis proved that homes listed on Zillow sell for 1.3% less, on average, than homes that were not on Zillow. The Zillow Tax on the U.S. median existing-home sale price of $430,000  translates to a $5,590 loss. 


The “Zillow Tax” Hurts Sellers 


Zillow wasn’t created to protect homeowner value – it is a lead-generation website built to make Zillow money at the expense of sellers. Zillow sells leads, not homes.

There is not a single feature on a Zillow listing page built to help sellers protect the value of their home; in fact, Zillow reduces the home’s sales price:

  • Days on Market: When a buyer sees a home that’s been on the market a long time, their perception is that there is something wrong with the property.
  • Price Cut History: Publicly showing every price cut makes it look like the seller is desperate, which encourages buyers to ask for even bigger discounts.
  • Algorithmic Zestimate: Often the Zestimate is less than the value of the home.
  • Climate Risk, Flood Risk & Fire Risk: By showing these unofficial and arbitrary risks, Zillow makes the home look less valuable.
  • False Advertising: Zillow routes buyers to third-party agents who paid for the lead and often divert the buyer inquiry away from the home. A Wharton School study found that nearly 99.7% of consumers mistakenly believe that Zillow’s “Contact Agent” button connects them to the listing agent.

Independent research points the same direction. Dr. Darren Hayunga, a professor at the University of Georgia, studied 20 years of Dallas-Fort Worth home sales and found that sellers who avoided the “negotiation discount” from having days on marketing and price drop history  on the MLS and Portals sold for 1.7% more, with the premium jumping to over 8% for luxury properties.


Why Do Some Of The Largest Home Builders Avoid Zillow


If exposure on Zillow was truly necessary to maximize price, the most sophisticated home builders in the world would rely on it. But they do not.

80 Clarkson Street, the condominium built by Zeckendorf Development, achieved over $1 Billion in contracted sales, including the most expensive home in downtown Manhattan history, without a single listing ever appearing on Zillow. If Zillow truly helped them get the best price, these industry leaders would certainly be using it.


Protecting Your Home’s Value


The “Zillow Tax” isn’t inevitable. Sellers have a choice. By choosing a phased marketing strategy, sellers can test price, receive feedback, build buyer interest and create buyer urgency before the clock starts, and reduce risk.


Methodology

Compass economists analyzed 296,966 Compass listings posted between January 2025 and May 2026, 806 of which experienced a Zillow ban.

The median sale-to-list price ratio for banned listings is 100%, compared with 98.7% for non-banned listings. Using quantile regression, we can confirm the difference of 1.3 p.p. (± 0.8 p.p.) is statistically significant. Additionally, 50.5% of banned listings sell at or above their list price, compared with 44.6% of non-banned listings—a difference of 5.9 p.p. (± 5.6 p.p.) that is also statistically significant. This trend persists when controlling for market, price, agent, and pre-marketing strategy.

The analysis also found that when comparing homes banned by Zillow to homes not banned by Zillow, there is no significant difference in the likelihood or speed of a home going under contract.

For listings banned by Zillow, 34% signed a contract within 30 days, compared with 36% of non-banned listings. The observed raw difference of -2.1 percentage points falls within the margin of error (± 3.3 p.p.) and is statistically insignificant. Controlling for market, price, and agent results in a difference of 2.5 p.p. (± 3.2 p.p.), which remains statistically insignificant. We measured the likelihood of homes going pending in all time horizons—not just 30 days—and found no significant difference in performance between banned and non-banned listings.

Market Trends • July 28, 2026

Roseville and Granite Bay Real Estate Market Update: July 2026

Wondering if now is a good time to buy or sell a home in Roseville or Granite Bay? The latest market data shows both communities remain strong, but each offers different opportunities for buyers and sellers.

Here’s what you need to know about the July 2026 housing market.

Roseville Real Estate Market Remains Competitive

Roseville continues to be one of the Sacramento region’s most desirable places to live. With excellent schools, parks, shopping, and convenient access to major employers, buyer demand remains steady.

Roseville Market Highlights

  • Average Sales Price: $730,000
  • Median List Price: $707,000
  • Average Sale-to-List Price: 99.8%
  • Homes Sold: 137
  • Months of Inventory: 2.64

Although inventory has increased by 25% compared to the previous three-month average, the market still favors sellers. Less than three months of inventory means well-priced homes continue to sell quickly.

What This Means for Sellers

If you’re considering selling your Roseville home, buyers are still willing to pay close to asking price. Proper pricing, professional photography, and strategic marketing remain the keys to attracting strong offers.

What This Means for Buyers

The increase in available homes gives buyers more choices than earlier this year. While competition still exists, there is more opportunity to find the right home without the intense bidding wars that defined recent years.


Granite Bay Luxury Market Continues to Perform Well

Granite Bay remains one of Northern California’s premier luxury real estate markets. Buyers continue to seek larger homes, custom properties, and neighborhoods known for top-rated schools and an exceptional quality of life.

Granite Bay Market Highlights

  • Average Sales Price: $1.49 million
  • Median List Price: $1.35 million
  • Average Sale-to-List Price: 97%
  • Homes Sold: 24
  • Months of Inventory: 2.96

Home values continue to show strength, with the average sales price increasing 5% over the previous three-month average.

What This Means for Sellers

Low inventory continues to benefit Granite Bay homeowners. Buyers remain active, especially for homes that are updated, well-maintained, and priced appropriately.

What This Means for Buyers

Luxury buyers have more negotiating room than they did during the height of the market, but desirable properties are still moving quickly. Being prepared with financing and working with an experienced local agent can make a significant difference.


Is It a Buyer’s or Seller’s Market?

Both Roseville and Granite Bay remain seller-leaning markets, but conditions are becoming more balanced.

For sellers:

  • Low inventory continues to support home values.
  • Well-prepared homes are attracting strong offers.
  • Pricing correctly is more important than ever.

For buyers:

  • Inventory is slowly improving.
  • There are more options available than earlier this year.
  • Homes are still selling quickly, so preparation is key.

Thinking About Buying or Selling?

Every neighborhood has its own market trends. The value of your home depends on much more than citywide averages, including location, condition, upgrades, lot size, and current buyer demand.

If you’re thinking about buying or selling in Roseville, Granite Bay, Rocklin, Loomis, Lincoln, or the surrounding Placer County communities, I’d be happy to provide a personalized market analysis and answer your questions.

Whether you’re planning a move this year or simply want to know what your home is worth, having current local market information can help you make confident decisions.

Contact me today for a complimentary home value consultation or to discuss your real estate goals.

Here are a few Questions and Answers:

Is it a good time to buy a home in Roseville, CA?
Yes. Buyers have more inventory than earlier this year, while home values remain relatively stable. Working with a local real estate professional can help you identify opportunities in a competitive market.

Is Granite Bay a seller’s market?
Yes. With less than three months of inventory and rising average sales prices, Granite Bay continues to favor sellers, particularly in the luxury home segment.

How much are homes selling for in Roseville?
As of July 2026, the average sales price for a single-family home in Roseville is approximately $730,000, with homes selling for nearly 100% of their asking price on average.

How much are homes selling for in Granite Bay?
The average sales price for a single-family home in Granite Bay is approximately $1.49 million, reflecting continued strength in the luxury housing market.

Market Trends • July 21, 2026

What To Expect from the Housing Market in the Second Half of 2026

If the first half of this year has left you feeling stuck, you’re not the only one. Mortgage rates stayed higher than people wanted. Affordability remained tight. And uncertainty overseas added another layer of pressure nobody saw coming.

That’s why so many people are asking the same question: Will the second half of the year be any better for the housing market?

While nobody has a crystal ball, there are a few encouraging signs things could start moving in a better direction. Here’s what to watch.

Mortgage Rates Could Be Near a Turning Point 

One of the biggest reasons mortgage rates haven’t come down yet is inflation. And higher energy prices and uncertainty overseas are at least part of the reason inflation is still elevated. The encouraging news?

Oil prices have already started coming back down.

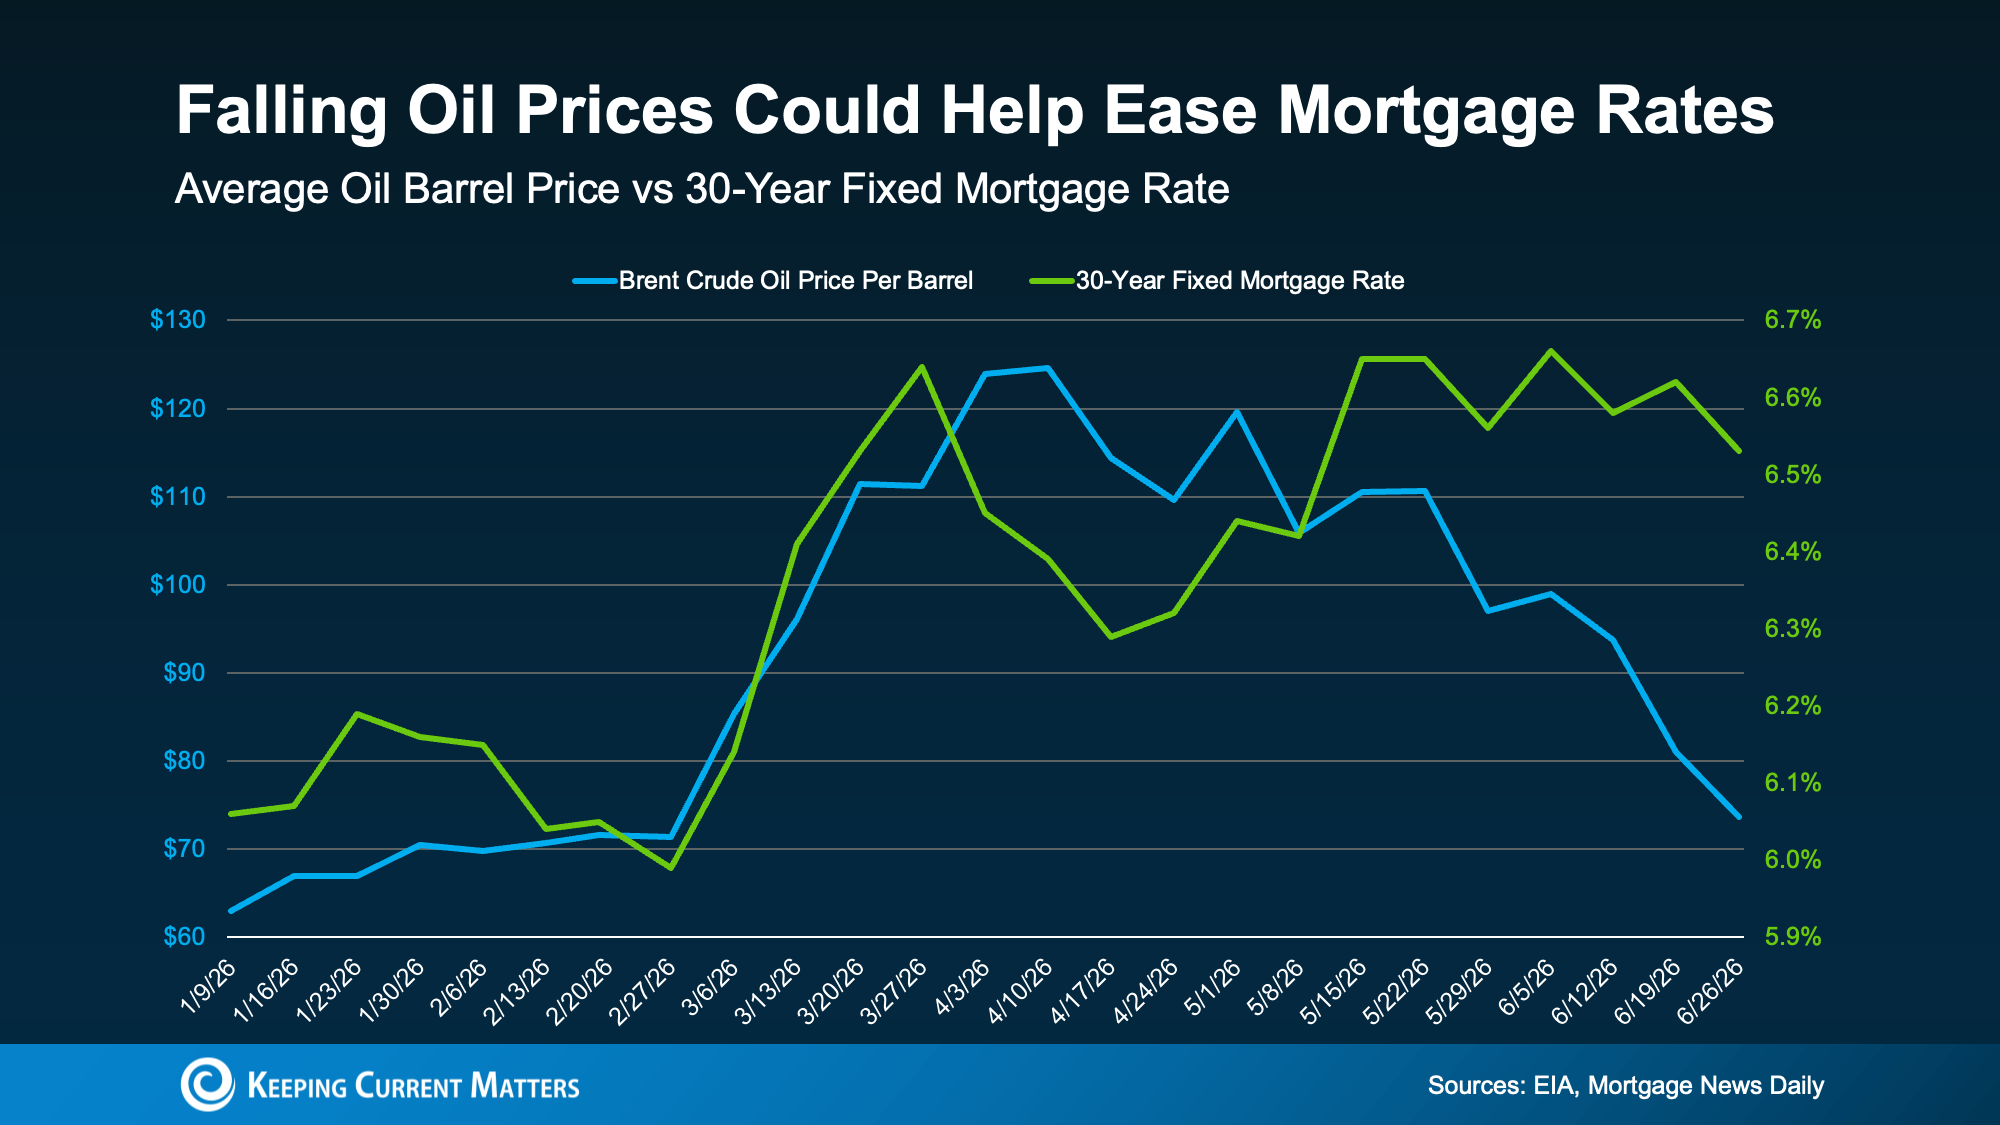
That may not sound like it has much to do with buying a home. But historically, mortgage rates and oil prices tend to move in the same direction.

Take a look at the graph below. Generally, they rise and fall together. Both went up in February when the conflict began. While there’s been some volatility lately, experts at the U.S. Energy Information Administration (EIA) say oil prices are forecast to come down. And since oil prices have been on an overall downward trend lately, mortgage rates could come down too:

a graph showing the price of a mortgage rate

It’s too soon to say exactly when that will happen (or by how much they’ll fall), but if energy prices go down, inflation cools off, and tensions overseas ease, mortgage rates could come down in the second half of the year.

And that’s good news for anyone thinking about moving. The first half of the year tested everyone’s patience. The second half may finally reward it.

Home Prices Could Pick Back Up

A lot of people want home prices to fall too. But that’s not what most forecasts show.

While price trends are going to vary by area, and some places are seeing mild declines, experts still expect home prices to net positive this year at the national level.

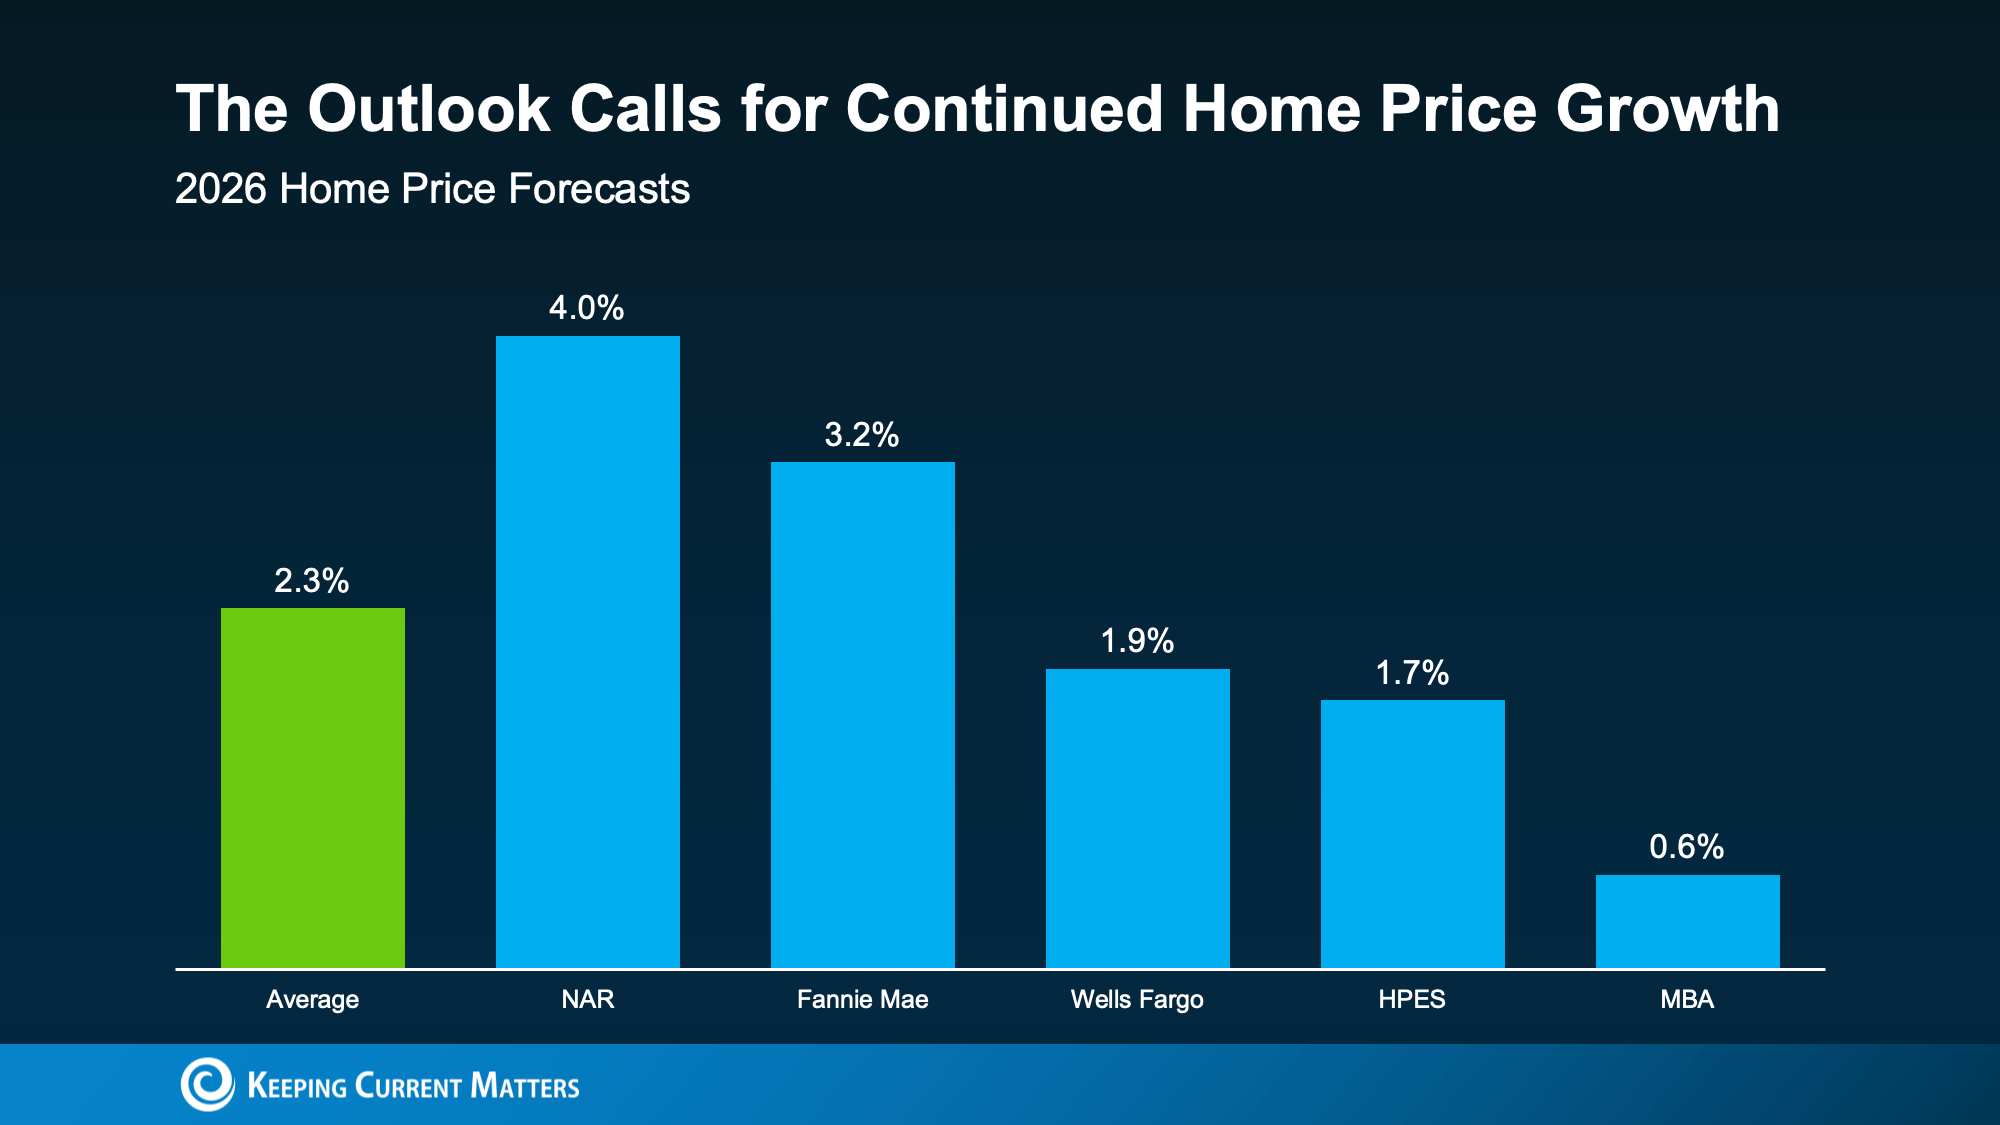
In fact, they’re projecting prices will rise by an average of 2.3% in 2026 (see graph below):

a graph of blue rectangular objects

What does that mean for you? Right now, Federal Housing Finance Agency (FHFA)data shows prices are up about 1.7% nationally year-over-year. The average forecast for all of 2026? 2.3%.

Based on those projections, home price growth would have to pick up a bit during the second half of the year. Nothing dramatic, just enough to finish the year around that projected 2.3% gain.

Here’s why that’s possible.

The number of homes for sale has grown, but that growth may be starting to slow down. And if rates improve, more buyers could jump back into the market. More buyers competing could put modest upward pressure on prices, especially if inventory’s not growing as fast.

That’s why buyers shouldn’t assume waiting will guarantee a lower price later. And for sellers, that’s great news if you’ve been worried about your home’s value.

More Homes Are Expected To Sell

If you’ve been wondering why the housing market has felt quieter lately, you’re not imagining it. Home sales have been slower than many experts expected. But that doesn’t mean people have stopped wanting to move.

A lot of people still want or need to make a change. They’ve just been waiting for more certainty, better affordability, or a clearer read on where the market is headed. And early signs show that may be on the horizon.

If rates ease and confidence improves, more people may finally move. As Odeta Kushi, Deputy Chief Economist at First American, explains:

“Overall, we expect pent-up demand to continue emerging gradually. But the pace of recovery will vary significantly across markets and will depend on the path of rates, labor market conditions and inventory growth.”

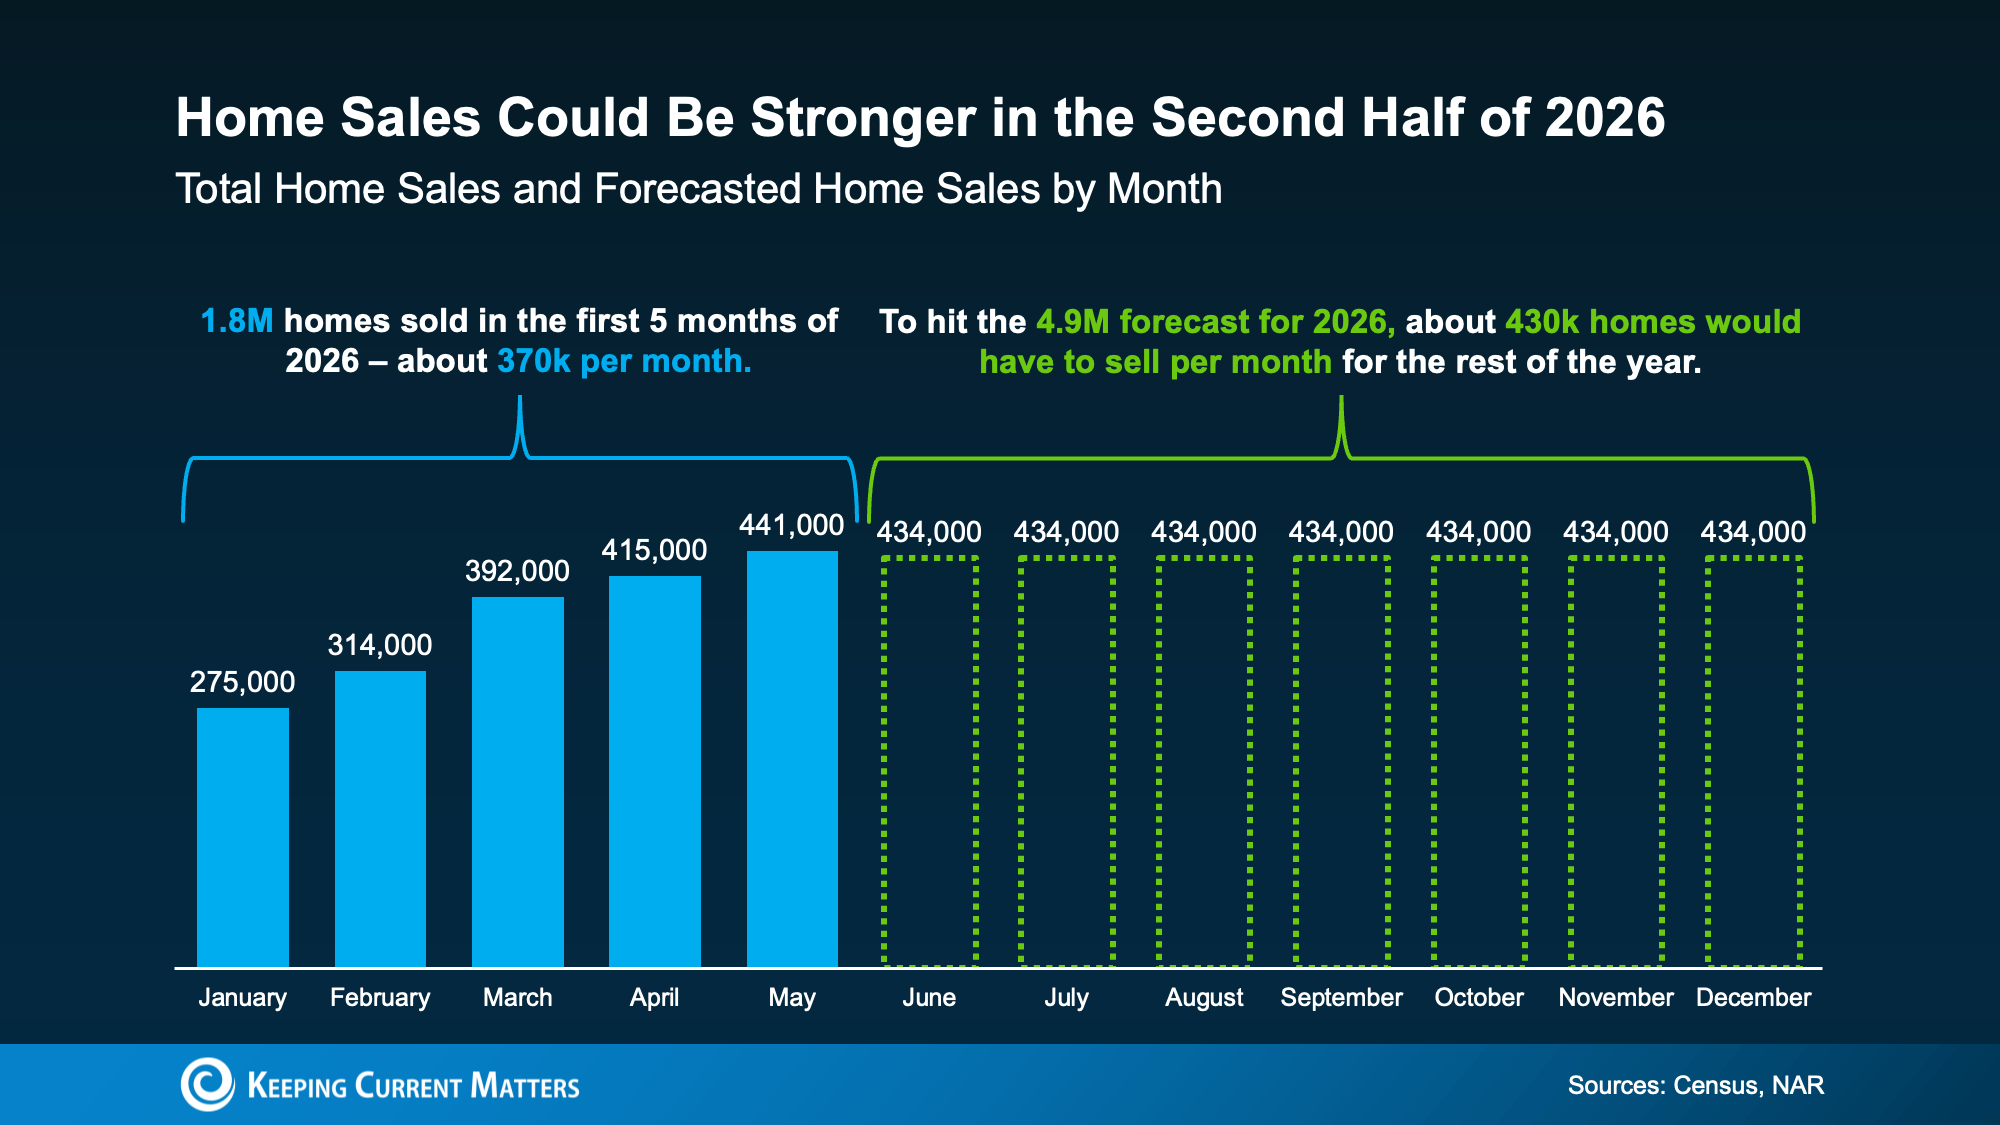
Based on the latest forecasts, to hit the number of sales expected this year, here’s what would have to happen. The second half of the year would need to outperform the first in sales (see graph below):

a graph of sales and statistics

In fact, each month for the rest of 2026 would have to come close to matching the best month we’ve had so far this year (May). That’s a sign the experts are calling for more momentum headed into the second half.

More people will finally make their move happen – and you’ve got the chance to be one of them.

Bottom Line

The second half of the year probably won’t be perfect. But it could be better.

Mortgage rates may ease. Home sales could pick up. And prices are expected to continue rising at a healthier, more sustainable pace. If you’ve been waiting for signs of progress, this is it.

If you want to understand what these forecasts mean for your plans and what’s happening in your local market, give me a call.


Keeping Current Matters
Market Trends • July 14, 2026

Think Home Prices Will Crash? Here’s What the Experts Actually Expect.

One of the biggest reasons buyers are still sitting on the sidelines is because they think home prices are going to come down.

  • Some believe a crash is coming and they’ll get a better deal if they hold off.
  • Others worry they’ll buy now and watch their home’s value fall later.

And nobody wants to overpay or buy right before values drop. But here’s the question worth asking:

What if the crash you’re waiting for isn’t actually coming?

Because that’s what the latest data suggests.

Experts Are Not Calling for a Crash

If you’ve spent any time online lately, you’ve seen posts claiming home prices are about to come crashing down. And it’s true that some markets are seeing small price declines right now.

But that’s not the same thing as a nationwide crash.

While some places are going through a price adjustment, Realtor.com data shows home prices are still rising in 71% of housing markets across the country.

The trouble is, since negative news sells, you’re seeing more coverage about how a handful of markets are seeing declines, than how the majority are still seeing prices rise. And that’s unfortunate.

It’s exactly why a lot of buyers end up with the impression that prices are falling everywhere when they’re not. So how do you really know where prices are really headed from here?

That’s where the Home Price Expectations Survey (HPES) from Fannie Mae comes in.

Home Prices Will Rise for the Next 5 Years

Every quarter, more than 100 economists, housing experts, and market analysts are asked where they think home prices are headed based on the latest data available.

And despite all the uncertainty in today’s market, there’s one thing they largely agreed on:

They don’t think a crash is coming.

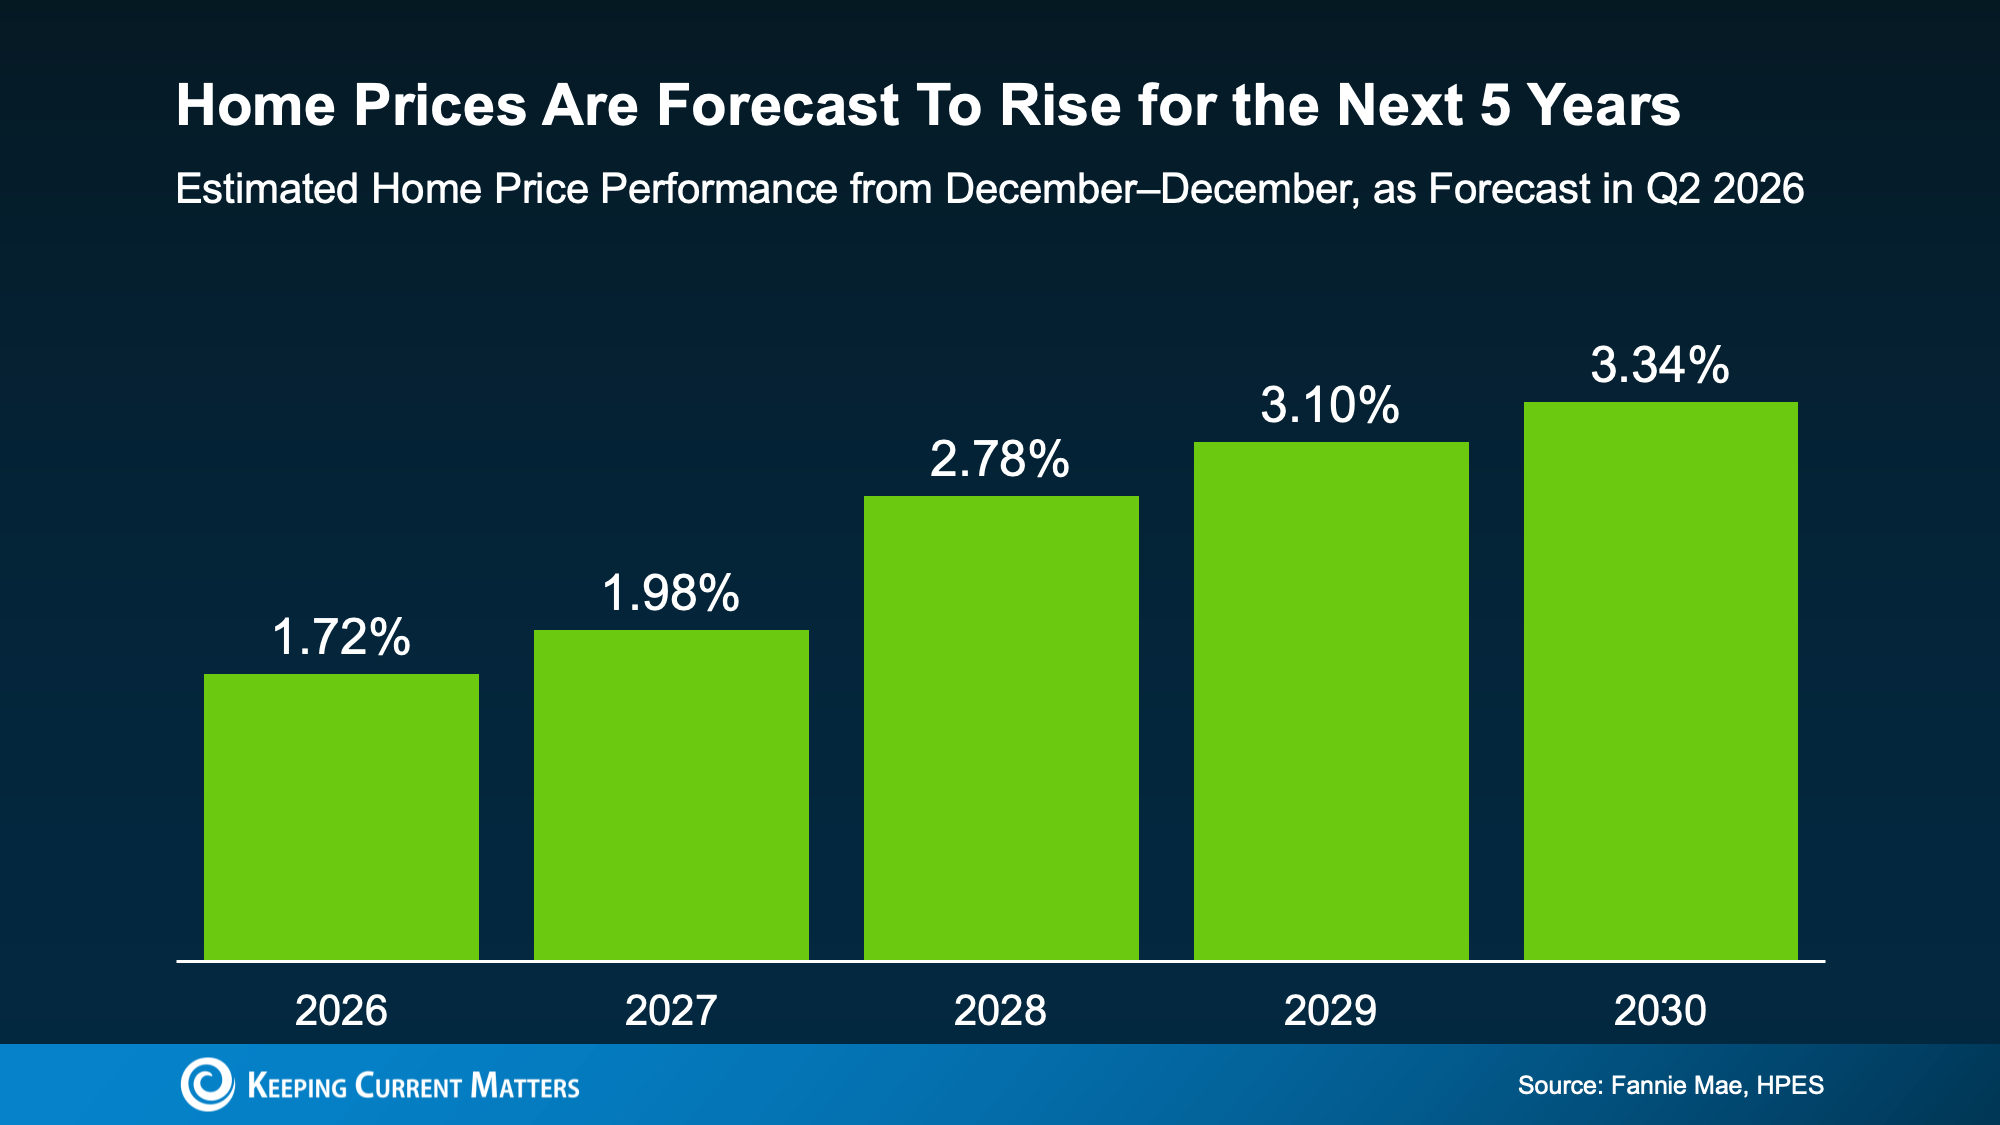
In fact, the average of all of their forecasts calls for home prices to rise every year for at least the next 5 years (see graph below):

a graph with green rectangles and numbers

The point is that the overwhelming expectation isn’t for prices to fall. It’s for prices to rise at a more normal pace. And just in case you’re looking at the forecasts and saying: “of course they’d say that” – know that this survey doesn’t just include optimists. It includes pessimists too.

Even the Pessimists Aren’t Predicting a Crash

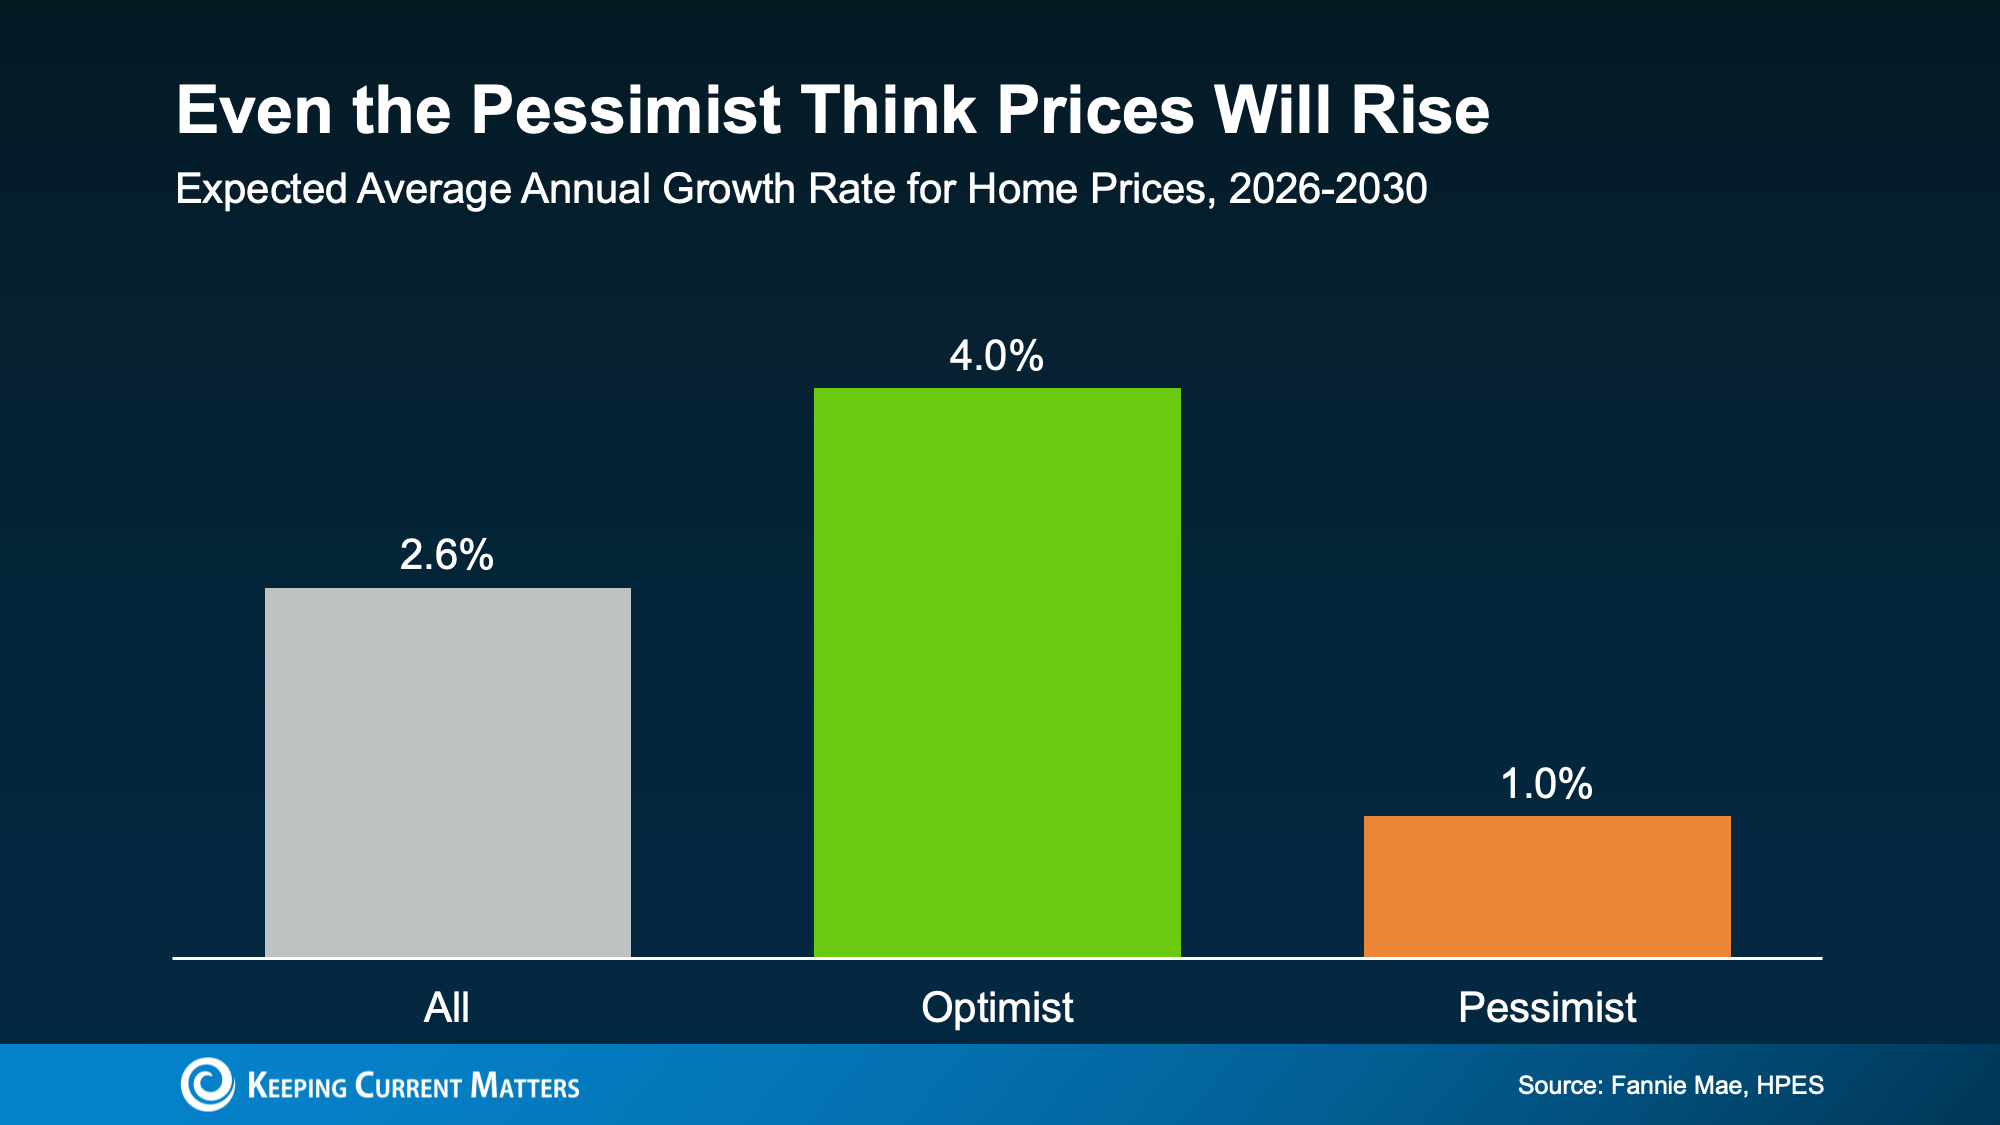
Researchers broke the panel into groups based on how bullish or bearish they were about housing. The result? Even the most pessimistic group still expects home prices to climb over the next five years.

Optimists think we’ll see prices go up roughly 4% a year. Pessimists say it’ll be closer to 1%. The reality may be somewhere in the middle.

a graph of growth rate for home prices

Think about that for a second. The debate among experts isn’t whether prices will crash. It’s how much they’ll rise.

That’s a very different conversation than the one happening across social media.

This Means Waiting Could Actually Cost You

So, if you’re putting off your move until prices come down, you may be disappointed. According to the experts, a widespread crash isn’t in the cards.

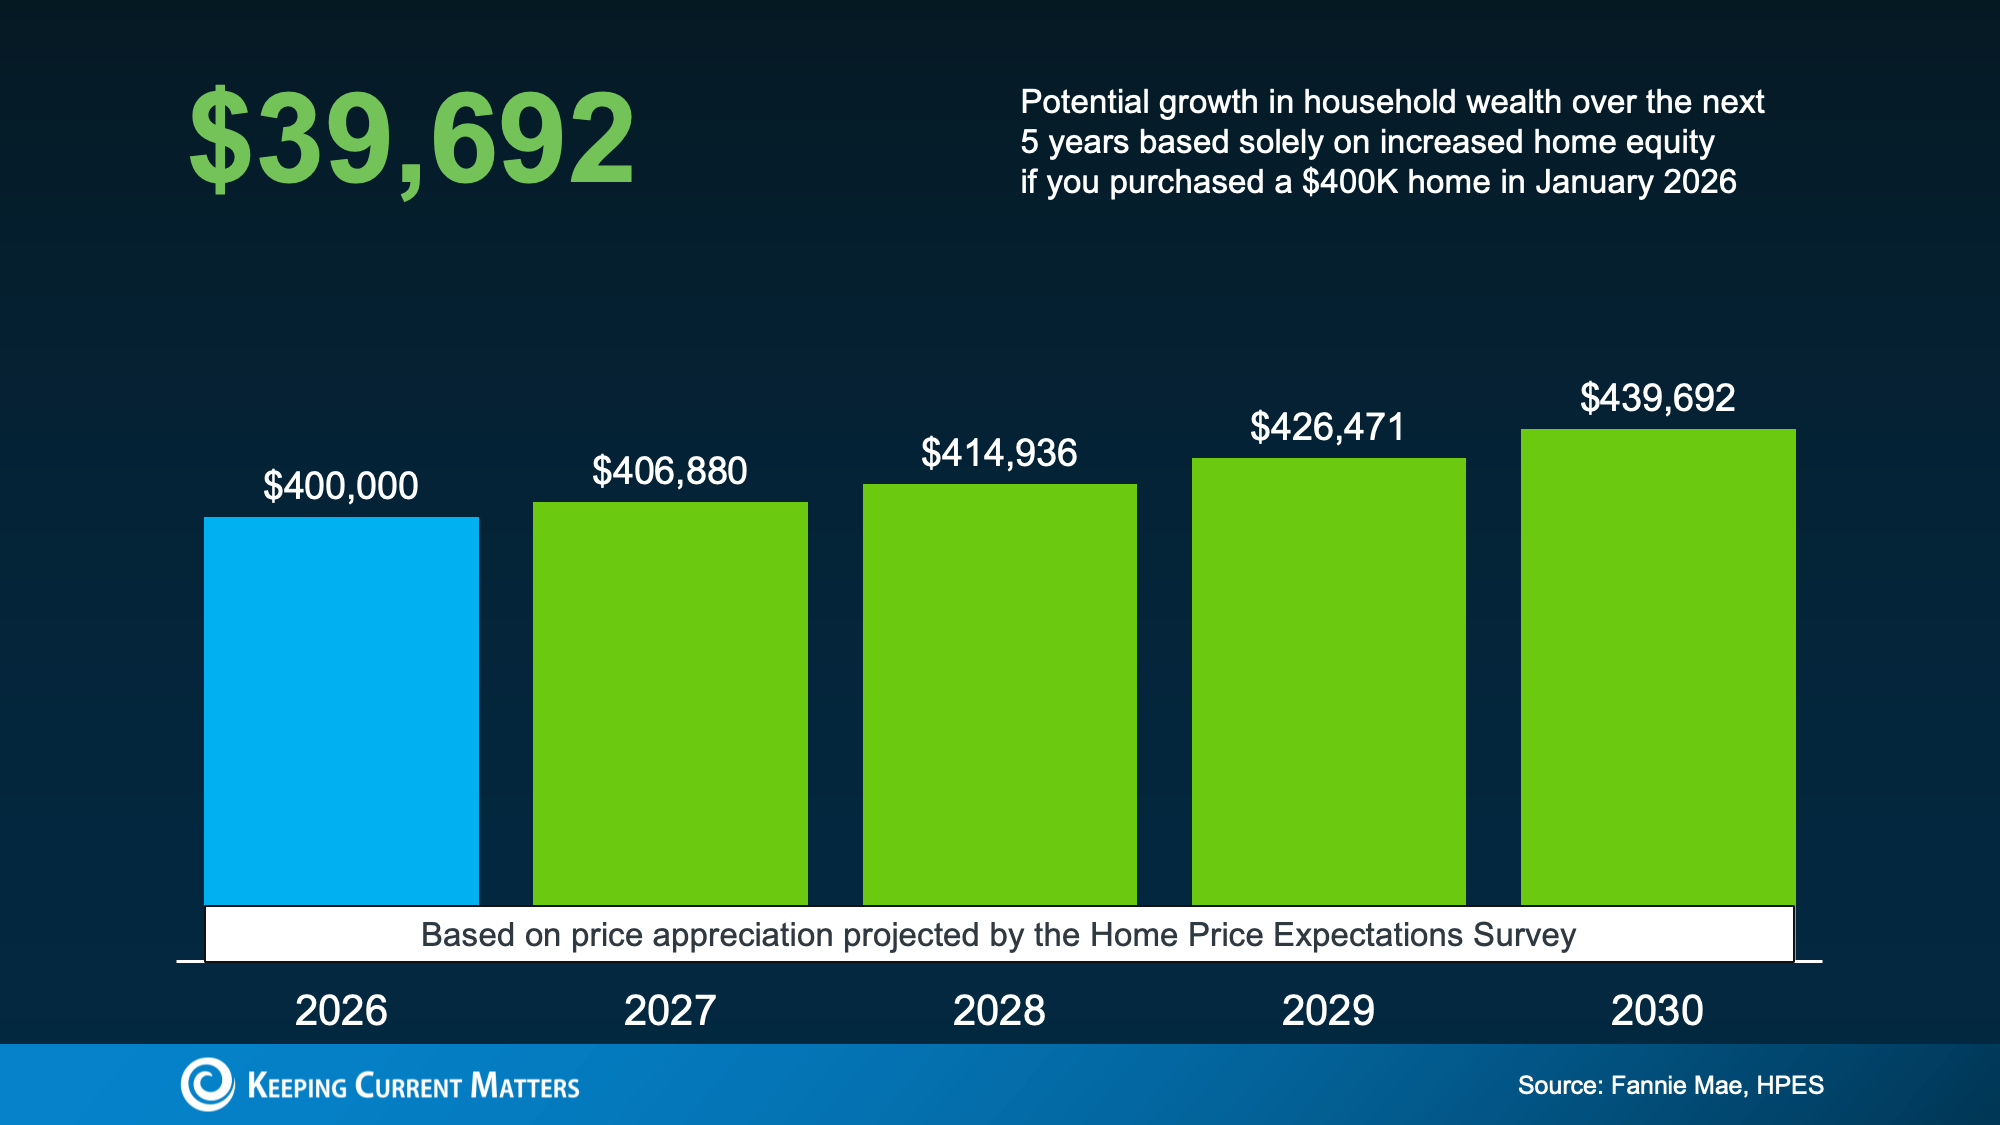
In fact, based on the HPES forecast, a buyer who purchased a $400,000 home this January would gain nearly $40,000 in equity over the next five years from appreciation alone, even in this more moderate market (see below):

a graph of growth in a chart

Of course, this all depends on local market conditions. This forecast is a national average. But broadly speaking, if the experts are right, the bigger risk isn’t that prices will crash. It may be waiting for a crash that never comes.

Because depending on your market, if you wait, you could be missing out on $40k in equity or paying 40k more in 5 years for the same house.

Bottom Line

A lot of buyers are waiting because they think prices will fall, but that’s not what the experts are saying.

If you’re trying to decide whether waiting still makes sense, give me a call. I can help you understand what’s happening in your local market and what it could mean for your plans.


-Keeping Current Matters